Unleash the power of AI in accounting. Expert-led, AI-augmented financial management — audit-ready, investor-ready, and always on time.
See how it works →
Vendor Fraud Prevention: A Practical Control Framework for Accounts Payable Teams
In This Blog Post
Share This Article
Last Updated: Nov 4, 2026
🔊 Listen
Vendor fraud rarely begins with an obviously fraudulent payment. More often, it starts with a small weakness somewhere in the accounts payable process. It could be an unverified new vendor, a bank detail change approved through email, a duplicate invoice that slips through, or one employee having too much control over the payment process.
That is why effective vendor fraud prevention requires multiple controls working together.
AP teams should independently verify new vendors and banking changes, separate vendor setup from payment approval, match invoices against purchase orders and receipts, and establish clear approval limits. Vendor master data should also be tightly controlled, while duplicate invoices, unusual payment patterns, and suspicious transactions should be regularly monitored.
Automation can make these checks faster by identifying anomalies and exceptions, but human oversight remains critical, particularly when payment instructions suddenly change.
The strongest AP teams treat fraud prevention as part of everyday payment discipline, not as a separate compliance task. When verification, approvals, monitoring, and reconciliation work together, businesses gain much stronger control over who gets paid, how much gets paid, and where the money goes.
TL;DR
Independent vendor and bank detail verification is important before approving payments.
Segregation of duties reduces the risk of unauthorized or manipulated transactions.
Three-way matching helps validate invoices before they move to payment.
Clear approval thresholds strengthen control over high-value and unusual transactions.
Vendor master data should be tightly restricted, monitored, and regularly reviewed.
AP automation helps flag duplicates, unusual patterns, and suspicious payment activity, making vendor fraud prevention faster and more consistent.
Accounts payable (AP) teams implement vendor fraud prevention by enforcing strict internal controls, like three-way invoice matching, independent verification of banking details, dual-authorization payment thresholds, and automated anomaly monitoring.
Fake invoices altered bank details, and impersonated suppliers can slip through when verification is informal or controls are missing. A proactive vendor fraud prevention framework closes those gaps before payments go out and protects your cash flow.
This blog outlines practical accounts payable internal controls, verification workflows, and early-warning detection strategies to keep your payment pipelines safe.
Protect Every Payment
Get expert support to verify vendors, secure payments, and reduce fraud risk.
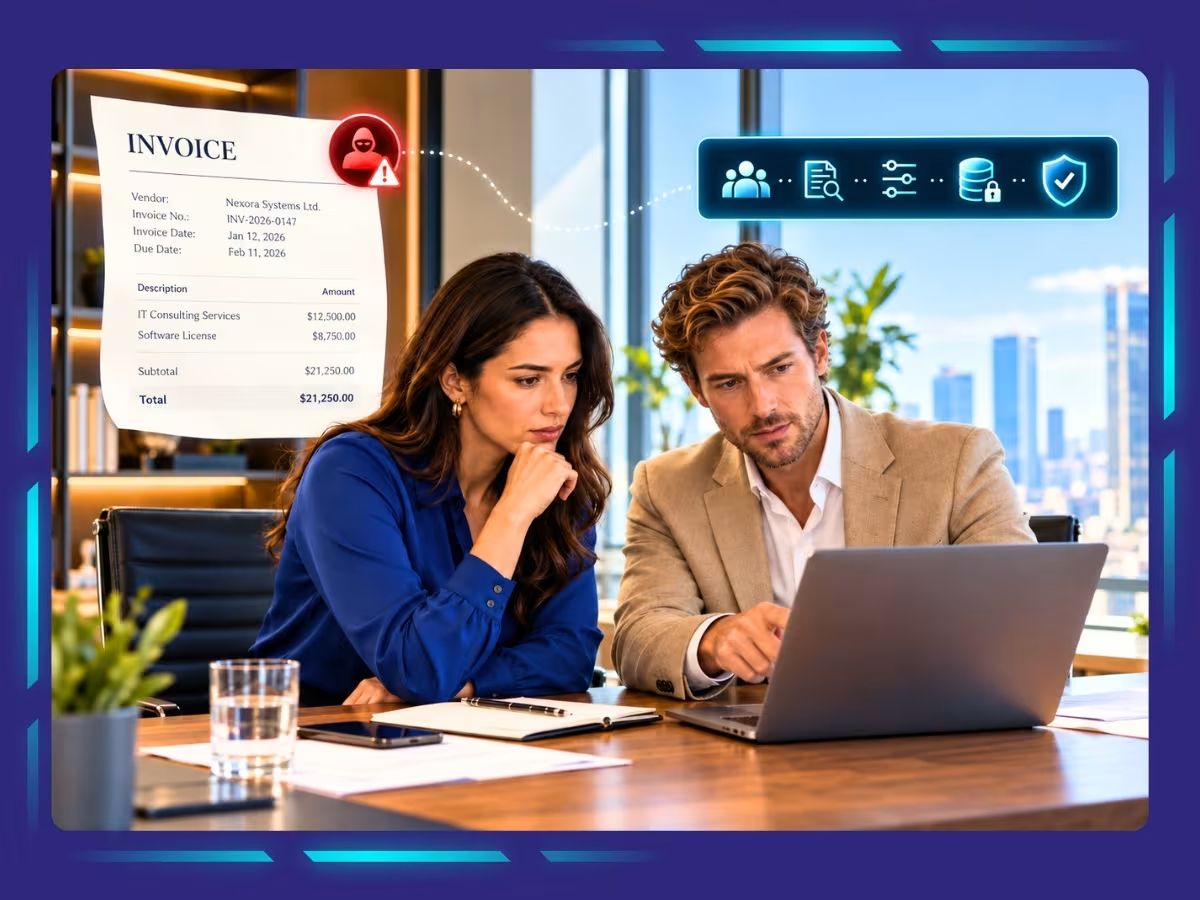
Vendor fraud in accounts payable happens when someone manipulates vendor information, invoices, approvals, or payment details. That someone can be a supplier, an employee, an outside fraudster, or colluding parties working together, and they aim to divert company funds or collect payments they have no right to receive.
Vendor fraud poses a severe financial threat to modern businesses. According to the 2026 AFP Payments Fraud and Control Survey, 74% of US organizations were affected by business email compromise (BEC) in a 2025, a common route for fake invoices and fraudulent bank detail changes.
The schemes range from fake vendors and impersonated suppliers to altered bank details, duplicate or inflated invoices, and employee-vendor collusion. Knowing where each one enters the AP cycle is the first step toward placing the right controls.
Where Vendor Fraud Typically Occurs in the Accounts Payable Process?
Vendor fraud can enter the AP cycle at several points, particularly where verification is informal; responsibilities overlap, or changes are approved without independent checks. Understanding these risk points helps AP teams place vendor fraud prevention controls where they are most likely to prevent or detect fraud.
Vendor Onboarding
Fraud can begin when a fake, shell, or improperly verified supplier is added to the vendor master. Weak onboarding checks may allow false business details, duplicate vendors, or undisclosed employee connections to go unnoticed before invoices start entering the AP workflow.
Vendor Master Data Changes
Changes to bank accounts, email addresses, payment instructions, or contact details create a major fraud risk. A fraudster may impersonate a legitimate supplier and request updated payment information, redirecting future payments unless the change is independently verified.
Invoice Submission
Fraudulent invoices may include duplicate charges, inflated amounts, fabricated services, altered bank details, or invoices from unauthorized vendors. Risks increase when invoices are accepted directly by email without validating them against approved vendor records and supporting documentation.
Invoice Approval
Weak or inconsistent approval processes can allow fraudulent invoices to progress. This may include managers approving without reviewing supporting documents, employees approving transactions outside their authority, or collusion between internal staff and vendors to push through improper payments.
Purchase Order and Receipt Matching
Where PO matching is weak or bypassed, invoices may be paid without confirming that the goods or services were actually ordered and received. Fraudulent suppliers may exploit missing purchase orders, incomplete receipt records, or manual overrides to support false claims.
Payment Preparation and Release
Payment fraud can occur when payment files, beneficiary information, payment amounts, or approval limits are manipulated before release. The risk is higher where one person can both prepare and approve payments or where bank details are changed shortly before a payment run.
Post-Payment Reconciliation and Review
Fraud may remain undetected when bank reconciliations, vendor statement reviews, and payment exception checks are delayed or incomplete. Duplicate payments, unusual vendor activity, unexplained adjustments, or payments to inactive suppliers can continue if post-payment monitoring is weak.
The Core Vendor Fraud Prevention Framework for Accounts Payable Teams
An effective vendor fraud prevention framework should place controls across the full AP cycle, from vendor setup to final payment review. The goal is not to rely on a single approval step, but to layered accounts payable internal controls that make fraudulent changes, invoices, and payments harder to process unnoticed.
Verify Every New Vendor Before Onboarding
Require supporting business information before creating a vendor record. This can include tax details, registration documents, contact information, bank verification, and confirmation that the supplier has been properly approved. Independent verification helps prevent fake or unauthorized vendors from entering the AP system.
Independently Verify Bank Detail Changes
Never rely only on an email requesting updated payment instructions. Confirm bank account changes through a trusted contact method already on file, such as a verified phone number. High-risk changes should also require a second internal approval before they become effective.
Separate Vendor Setup, Approval, and Payment Duties
No single employee should control the entire AP process. Vendor creation, invoice processing, payment approval, and bank reconciliation should be assigned to different people wherever possible. This reduces the opportunity for one person to create and pay a fraudulent transaction without detection.
Match Invoices Against Purchase Orders and Receipts
Use two-way or three-way matching to compare invoices with purchase orders and evidence that goods or services were received. Differences in quantities, pricing, vendor details, or payment terms should be reviewed before the invoice is approved for payment.
Use Defined Approval Limits
Set clear approval thresholds based on transaction value, vendor type, and risk level. Higher-value or unusual payments should require additional approval. Approval limits should also be configured in the AP or ERP system, so they cannot be easily bypassed.
Detect Duplicate and Unusual Invoices
Check invoice numbers, dates, amounts, vendor names, and bank details for duplicates or unusual patterns. AP automation can help flag repeated invoices, round-dollar amounts, split transactions, or invoices that fall just below approval thresholds.
Restrict Access to Vendor Master Data
Limit the ability to create or edit vendor records to authorized users. Sensitive changes should be logged, reviewed, and approved. Regularly review user permissions to ensure former employees or staff who no longer require access cannot modify vendor information.
Review Vendor and Payment Activity Regularly
Conduct periodic reviews of vendor master data and payment history. Look for dormant vendors becoming active, repeated bank changes, unusual payment frequency, duplicate addresses, or unexpected increases in invoice values. Regular exception reviews can identify patterns that individual transactions may not reveal.
Protect Every Payment with Expert Accounts Payable Services
Vendor fraud prevention is strongest when controls are built into every stage of the accounts payable process, from vendor onboarding and invoice validation to approval, payment release, and reconciliation. Consistent verification, clear segregation of duties, and regular exception reviews help reduce the risk of fraudulent or unauthorized payments slipping through.
Whiz Consulting supports businesses with expert accounts payable services designed to strengthen accounts payable internal control and improve day-to-day AP operations. Our team helps with invoice processing, vendor management, approval workflows, payment support, reconciliations, and reporting, giving businesses a more structured and reliable AP process while helping internal teams maintain better oversight over every payment.
Shivangi is a fintech content expert with years of experience, specializing in healthcare accounting, real estate finance, accounts payable and NetSuite solutions. With sharp industry insights and deep accounting expertise, she helps companies turn numbers into actionable strategies for success.
Have questions in mind? Find answers here...
Bank changes should be verified independently using contact information already on file. AP teams should avoid relying only on email requests and should require a second approval for sensitive changes before the updated bank details are used for payment.
Strong controls include vendor verification, segregation of duties, three-way matching, defined approval limits, restricted vendor master access, duplicate invoice checks, and regular payment reviews. Using several controls together is more effective than relying on a single approval step.
Three-way matching compares the supplier’s invoice with the purchase order and proof that the goods or services were received. Differences in price, quantity, or other details can then be investigated before payment is approved.
Yes. AP automation can help detect duplicate invoices, enforce approval workflows, flag unusual payment patterns, maintain audit trails, and restrict manual overrides. However, automation should support human review rather than replace independent verification for high-risk transactions.
Segregation of duties prevents one person from controlling vendor creation, invoice approval, payment release, and reconciliation. Dividing these responsibilities reduces the opportunity for fraudulent transactions to be created and processed without independent review.
Vendor master data should be reviewed regularly, with higher-risk vendors receiving more frequent attention. Reviews can identify inactive vendors, duplicate records, unexplained bank changes, outdated information, or unusual vendor relationships.
Thousands of business owners trust
Whiz to manage their account
Let us take care of your books and make this financial year a good one.