

In This Blog Post
Share This Article
- Last Updated: Oct 7, 2026
- 🔊 Listen
TL;DR
- Standardized charts of accounts and accounting policies make consolidation more consistent and comparable.
- Intercompany transactions must be reconciled and eliminated to avoid distorted consolidated financial results.
- A structured consolidation process improves account mapping, reporting accuracy, and group-level financial visibility.
- Group-wide closing calendars and standardized procedures help speed up multi-entity month-end reporting.
- Consolidated reports help roll-ups monitor profitability, liquidity, acquisition performance, debt, and working capital.
- Audit-ready books require reconciled balances, documented eliminations, and a clear consolidation audit trail.
Multi-entity accounting in a business roll-up involves consolidating the financial records of acquired companies while maintaining accurate reporting for each entity. This requires standardizing charts of accounts, aligning accounting policies, reconciling intercompany transactions, and preparing consolidated financial statements. Without a structured approach, different accounting systems, inconsistent records, and complex
This guide explores how businesses can consolidate books across a roll-up in 2026; overcome acquisition adjustments can delay month-end close and affect financial visibility. common multi-entity accounting challenges, streamline financial reporting, and build scalable processes that support future acquisitions and informed financial decisions.
What Is Multi-Entity Accounting in a Business Roll-Up?
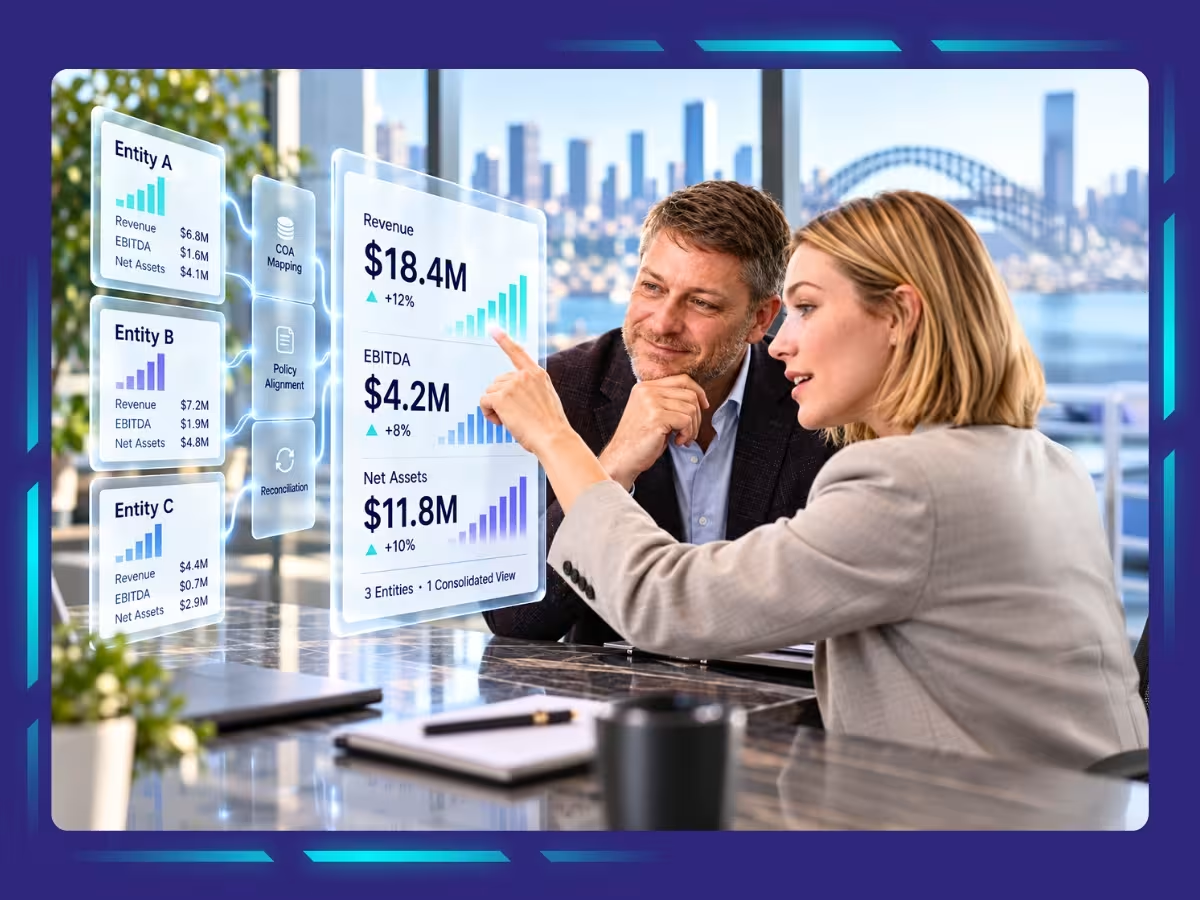
Multi-entity accounting involves managing the financial records of multiple acquired companies while consolidating their results into a single financial view. Since acquired businesses often have different accounting systems, reporting procedures, and financial structures, bringing their books together requires three essential activities:
- Maintaining Entity-Level Records: Track each acquired company’s revenue, expenses, assets, liabilities, and financial performance separately to preserve visibility into individual business operations.
- Standardizing Accounting Across Entities: Align charts of accounts, accounting policies, transaction classifications, and reporting periods to ensure financial information remains consistent and comparable.
- Consolidating Financial Reporting: Combine financial results across entities, eliminate intercompany transactions and balances, and prepare consolidated financial statements that show the roll-up’s overall financial performance.
What Makes Consolidating Books Across Multiple Entities Challenging?
Consolidating books across a business roll-up can be challenging because acquired companies often operate with different accounting systems, financial policies, and reporting practices. Bringing these records together requires businesses to address several issues that can affect consolidation accuracy, reporting consistency, and the speed of month-end close.
- Different Charts of Accounts and Accounting Policies: Acquired companies may classify revenue, expenses, assets, and liabilities differently or follow inconsistent accounting policies. These differences make account mapping difficult and can produce inconsistent consolidated results.
- Inconsistent Financial Reporting Periods: Entities may use different fiscal year-ends, reporting calendars, or transaction cut-off procedures. Without aligning reporting periods and making appropriate adjustments, businesses risk consolidating financial information from different timeframes.
- Multiple Accounting and ERP Systems: Acquired companies often use different accounting platforms, data structures, and reporting formats. Extracting, mapping, and integrating information from these systems can increase manual work and create data inconsistencies.
- Intercompany Transactions and Balances: Loans, sales, shared expenses, and fund transfers between group companies must be identified, reconciled, and eliminated during consolidation. Unresolved differences can distort consolidated revenue, expenses, assets, and liabilities.
- Incomplete Historical Financial Records: Newly acquired entities may have missing documentation, unreconciled balances, or inconsistent historical accounting records. These gaps can complicate opening balance validation, acquisition accounting, and the preparation of reliable consolidated statements.
- Different Month-End Closing Procedures: When entities follow different reconciliation schedules, approval processes, and reporting deadlines, consolidation can be delayed. Establishing a consistent group-wide closing calendar helps ensure financial information is available for timely reporting.
How to Consolidate Financial Statements Across a Roll-Up
Consolidating financial statements across a business roll-up requires combining financial data from acquired companies into a consistent group-level view. A structured process helps ensure accurate account mapping, aligned accounting policies, reconciled intercompany balances, and reliable financial reporting across all entities.
Step 1: Collect and Review Financial Data from Each Entity
Gather trial balances, general ledgers, financial statements, and supporting schedules from every entity. Review the records for missing transactions, unreconciled accounts, incorrect balances, and incomplete documentation. For newly acquired businesses, confirm acquisition dates and opening balances to establish a reliable starting point for consolidation.
Step 2: Map Entity-Level Accounts to a Consolidated Chart of Accounts
Map each entity’s existing chart of accounts to a standard group-level structure. Ensure that similar revenue, expense, asset, and liability accounts are classified consistently while retaining sufficient detail for individual entity reporting. This allows financial results from different accounting systems to be combined accurately.
Step 3: Align Accounting Policies and Reporting Periods
Review accounting policies across acquired companies and make necessary adjustments to ensure consistent treatment of revenue, expenses, depreciation, accruals, and other transactions. Align reporting periods and establish common cut-off procedures so that financial results are consolidated on a comparable basis.
Step 4: Reconcile Intercompany Transactions and Balances
Identify transactions between group companies, including intercompany sales, loans, shared expenses, and fund transfers. Reconcile corresponding receivables and payables, investigate discrepancies, and confirm that both entities have recorded transactions consistently before preparing consolidation entries.
Step 5: Record Consolidation Adjustments and Elimination
Prepare the necessary consolidation entries to eliminate intercompany revenue, expenses, receivables, payables, and other internal transactions. Record applicable acquisition-related adjustments, goodwill, non-controlling interests, and other consolidation entries in accordance with the relevant accounting framework.
Step 6: Prepare Consolidated Financial Statements
Combine the adjusted financial results of the parent company and its controlled subsidiaries to prepare the consolidated income statement, balance sheet, and cash flow statement. Ensure the statements reflect the group’s financial performance and position without double-counting transactions between entities.
Step 7: Review and Validate Group-Level Financial Results
Review consolidated balances against entity-level records, supporting schedules, and consolidation adjustments. Investigate unusual movements, confirm that intercompany balances have been eliminated correctly, and check that acquisition-related entries are complete. Document the review and obtain appropriate approval before issuing the consolidated statements.
How Should Intercompany Transactions Be Managed in Multi-Entity Accounting?
Managing intercompany transactions requires consistent recording, regular reconciliation, and accurate elimination of transactions between group companies. For businesses operating a roll-up, a structured approach helps prevent double-counting, resolve balance differences, and maintain reliable entity-level and consolidated financial reporting.
Identify Intercompany Sales, Expenses, and Transfers
Record transactions between group entities separately, including sales, shared expenses, management fees, and fund transfers. Use dedicated intercompany accounts and consistent transaction references so finance teams can identify corresponding entries across entities and distinguish internal activity from external transactions.
Reconcile Intercompany Receivables and Payables
Compare intercompany receivables recorded by one entity with the corresponding payables recorded by another. Perform regular reconciliations to identify missing invoices, timing differences, incorrect amounts, or transactions posted to the wrong accounts before preparing consolidated financial statements.
Account for Intercompany Loans and Interest
Maintain separate records for loans between group companies, including principal amounts, interest rates, repayment schedules, and outstanding balances. Ensure both entities record loan movements and interest consistently, with supporting documentation available for reconciliation and consolidation.
Eliminate Intercompany Transactions During Consolidation
Prepare consolidation entries to eliminate internal sales, expenses, receivables, payables, loans, and related interest. Where applicable, eliminate unrealized profits on transactions between group entities to prevent internal activity from overstating consolidated revenue, assets, or profitability.
Resolve Intercompany Balance Differences
Investigate differences between corresponding intercompany accounts before finalizing consolidation. Identify whether discrepancies arise from timing differences, missing transactions, currency conversions, or incorrect postings. Correct the underlying records where necessary and document any outstanding reconciling items to maintain a clear audit trail.
How Can Businesses Streamline the Multi-Entity Month-End Close?
A streamlined month-end close helps roll-up businesses consolidate financial information across multiple entities without unnecessary delays or repeated manual work. By establishing consistent procedures, clear responsibilities, and appropriate automation, finance teams can improve reporting accuracy and complete group-level financial statements on time.
Establish a Group-Wide Closing Calendar
Create a standard closing calendar that defines reporting deadlines, reconciliation schedules, and consolidation milestones for every entity. Set clear submission dates for trial balances, supporting schedules, and intercompany balances. A coordinated calendar helps identify delays early and ensures financial information is available when the group consolidation process begins.
Standardize Reconciliations and Journal Entries
Use consistent reconciliation templates, journal entry formats, and approval procedures across all entities. Establish common guidelines for accruals, depreciation, prepaid expenses, and other recurring adjustments. This reduces inconsistencies between acquired businesses, simplifies financial reviews, and makes it easier to consolidate entity-level results.
Assign Clear Responsibilities Across Entities
Define who is responsible for transaction recording, account reconciliations, intercompany matching, financial reviews, and final consolidation. Assign clear ownership and approval responsibilities at both entity and group levels. This helps prevent duplicated work, missed deadlines, and unresolved accounting issues during the closing process.
Automate Consolidation Adjustments Where Appropriate
Use accounting and consolidation software to automate recurring tasks such as account mapping, intercompany matching, currency conversion, and standard elimination entries. Establish appropriate review controls for automated adjustments and retain manual oversight of complex transactions, acquisition-related entries, and unusual balances.
Review Consolidated Results Before Reporting
Conduct a structured review of consolidated financial statements before finalizing the month-end close. Compare actual results against budgets, prior periods, and entity-level reports. Investigate unusual variances, confirm that intercompany eliminations are complete, and verify that consolidation adjustments are accurately recorded before issuing group-level financial reports.
Which Consolidated Financial Reports Should Roll-Up Businesses Review?
Roll-up businesses need financial reports that provide visibility into both individual entity performance and the group’s overall financial position. Reviewing the following reports regularly helps management assess profitability, monitor cash flow, evaluate acquisitions, and identify financial risks across the portfolio.
Consolidated Profit and Loss Statement
A consolidated profit and loss statement combines revenue, expenses, and profits across all entities while eliminating intercompany transactions. It helps management evaluate overall profitability, identify cost increases, compare operating margins, and understand how individual businesses contribute to the group’s financial performance.
Consolidated Balance Sheet
A consolidated balance sheet presents the group’s combined assets, liabilities, and equity after eliminating intercompany balances and recording applicable acquisition-related adjustments. It provides visibility into the roll-up’s financial position, including goodwill, outstanding debt, available cash, and other obligations arising from acquisitions.
Group-Level Cash Flow Statement
A group-level cash flow statement shows how cash is generated and used across operating, investing, and financing activities, excluding internal cash transfers between consolidated entities. It helps management assess liquidity, understand acquisition-related cash outflows, monitor debt repayments, and determine whether the group generates sufficient cash to support ongoing operations.
Entity-Level and Consolidated Budget vs. Actual
Budget-versus-actual reports compare financial performance against planned revenue, expenses, and profitability targets at both entity and group levels. They help management identify underperforming businesses, investigate unexpected costs, evaluate integration progress, and adjust financial forecasts based on actual operating results.
Acquisition Performance and Profitability Reports
Acquisition performance reports track how newly acquired businesses perform against their pre-acquisition financial projections and post-acquisition targets. Key measures may include revenue growth, operating margins, EBITDA, integration costs, and realized cost savings. These reports help management assess acquisition performance and identify where operational or financial improvements are needed.
Debt and Working Capital Report
Debt and working capital reports provide visibility into outstanding borrowings, repayment schedules, cash balances, receivables, payables, and short-term funding requirements. Reviewing these metrics at both entity and group levels helps management monitor liquidity, assess debt obligations, identify cash flow pressures, and plan financing for future acquisitions.
The Audit-Ready Standard for Multi-Entity Accounting
Audit-ready multi-entity books require accurate trial balances, reconciled intercompany accounts, documented eliminations, and consolidated financial statements supported by a clear audit trail. Under US GAAP, ASC 810 governs consolidation, while ASC 805 addresses qualifying business acquisitions. Maintaining these standards helps roll-up businesses meet four key requirements:
- Lender Compliance: Meet consolidated reporting and financial covenant requirements.
- Investor Reporting: Provide a clear view of group-wide financial performance.
- External Audits: Support reported figures with reconciliations and documented adjustments.
- Acquisition Due Diligence: Provide reliable consolidated records for prospective buyers and investors.
Establishing these practices early reduces reporting delays and simplifies future audits and acquisitions.
Simplify Multi-Entity Accounting with Expert Accounting Outsourcing Services
As a business roll-up expands, maintaining accurate financial records across multiple entities becomes increasingly complex. Standardized accounting processes, timely intercompany reconciliations, and reliable consolidated reporting are essential for maintaining financial visibility and supporting future acquisitions. A structured approach helps businesses reduce reporting delays, strengthen financial controls, and make informed decisions as their portfolio grows.
At Whiz Consulting, our expert accounting outsourcing services help businesses manage the financial complexities of multi-entity operations. From entity-level bookkeeping and chart of accounts standardization to intercompany reconciliations, month-end closing, and consolidated financial reporting, our accounting professionals help keep your books accurate, consistent, and audit-ready. We take care of your day-to-day accounting requirements so your team can focus on integrating acquisitions and growing your business.

Get customized plan that supports your growth

Have questions in mind? Find answers here...
Yes. Each legal entity should maintain its own accounting records, including a general ledger and trial balance. These records support entity-level reporting, tax obligations, reconciliations, and the preparation of consolidated financial statements.
Yes. Each legal entity should maintain its own accounting records, including a general ledger and trial balance. These records support entity-level reporting, tax obligations, reconciliations, and the preparation of consolidated financial statements.
Consolidated financial statements present a parent company and its controlled subsidiaries as one economic entity. Combined financial statements present multiple businesses together, often when they are under common control but do not have a conventional parent-subsidiary structure.
Each entity maintains its financial records in its functional currency. For consolidation, financial statements are translated into the group’s reporting currency using the applicable exchange rates and accounting requirements under ASC 830.
Maintain separate entity-level financial reports and monitor revenue, operating expenses, EBITDA, cash flow, and budget variances. Comparing these results with consolidated performance helps management assess each acquisition’s contribution to the overall group.
Thousands of business owners trust Whiz to manage their account
Let us take care of your books and make this financial year a good one.