

In This Blog Post
Share This Article
- Last Updated: Oct 9, 2026
- 🔊 Listen
TL;DR
- State reserve fund laws are increasing compliance requirements for HOA reserve funds accounting and condo reserve fund accounting.
- Reserve study, funding, disclosure, and reserve usage requirements vary significantly across different states and jurisdictions.
- Associations should maintain separate reserve accounts and implement detailed component-level tracking for major common assets.
- Reserve studies should guide annual budgets, contribution planning, and long-term repair and replacement funding strategies.
- Accurate financial reporting improves transparency, supports audits, and builds homeowner confidence in reserve fund management.
- Underfunded reserve accounts can lead to deferred maintenance, special assessments, financing needs, and increased financial risk.
- Outsourced accounting services help associations strengthen compliance, improve reporting accuracy, and manage evolving reserve fund regulations.
State reserve fund laws are reshaping HOA reserve funds accounting by introducing stricter requirements for reserve studies, funding levels, financial reporting, and long-term planning. In 2026, many HOA and condo associations must strengthen their accounting practices to remain compliant and financially prepared for future capital repairs and replacements.
Effective HOA reserve funds accounting helps associations maintain accurate records, improve budget forecasting, support regulatory compliance, and provide greater financial transparency. Understanding these evolving requirements is essential for boards and property managers looking to protect their communities from funding shortfalls and unexpected special assessments.

Simplify HOA Reserve Fund Accounting
Keep contributions accurate, records organised, and reporting clear.
What Are HOA and Condo Association Reserve Funds?
HOA and condo association reserve funds are savings set aside for major repairs and replacements of shared property, such as roofs, roads, elevators, HVAC systems, clubhouses, and pools.
Unlike operating funds, which cover everyday expenses like landscaping, utilities, and maintenance, reserve funds help associations prepare for significant future costs without relying on unexpected special assessments or loans. Proper HOA accounting ensures these funds are accurately tracked, adequately funded, and used in accordance with state laws and governing documents.
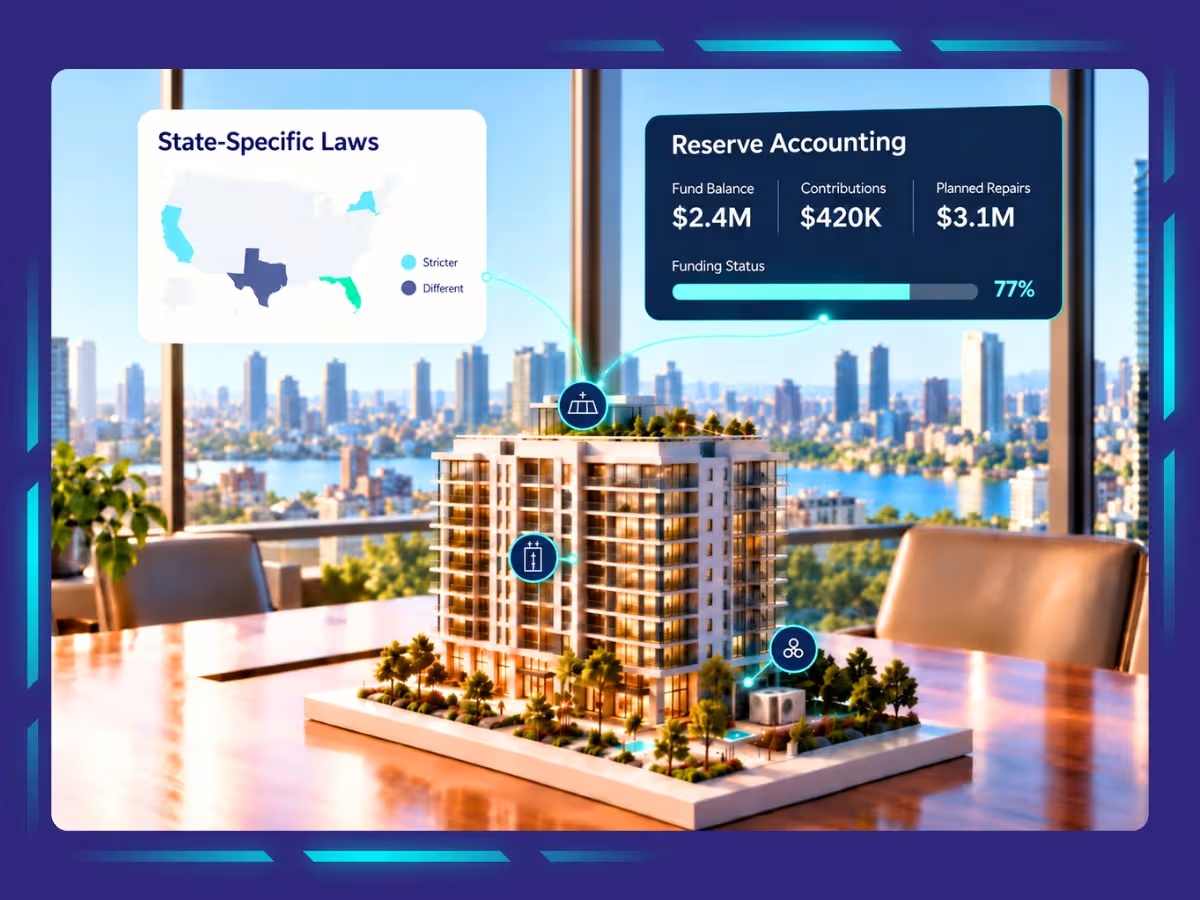
Moreover, reserve fund requirements vary by state. Some mandate reserve studies, funding, and disclosures, while others leave these decisions largely to association governing documents. Understanding these differences is essential for maintaining compliance and strengthening HOA reserve funds accounting.
How Reserve Fund Laws Differ Across States?
Reserve fund requirements vary by state, and, importantly, the rules do not always apply to both HOAs and condominium associations. Some states impose reserve-study or funding requirements specifically on condominiums, while others extend requirements to certain HOAs or community associations. These differences directly affect reserve budgeting, contribution levels, financial tracking, and long-term accounting.
- Florida (Condominiums): Qualifying residential condominium associations in buildings of 3 or more habitable stories are subject to Structural Integrity Reserve Study (SIRS) requirements. SIRS generally must be performed at least every 10 years and covers specified critical structural components.
- Nevada (HOAs/Community Associations): Reserve studies are generally required at least every 5 years, with the board reviewing reserve sufficiency annually and adjusting its funding plan when necessary.
- Maryland (HOAs and Condominiums): Maryland imposes reserve-study requirements on covered homeowners’ associations and condominium associations, generally requiring updates every 5 years. The study supports determining appropriate annual reserve funding.
- Hawaii (Condominiums): Hawaii has specific statutory reserve requirements for condominiums associations, including reserve studies and long-term reserve funding considerations.
- Colorado (Certain Community Associations): Colorado’s 2026 legislation adds reserve-study requirements for communities transitioning from developer control, including new planned communities and condominiums. The requirements therefore should not be presented as a blanket rule for every existing Colorado HOA.
Key State Reserve Fund Developments Affecting Associations in 2026
In 2026, states including Florida, Washington, Colorado, California, Maryland, and Hawaii are tightening reserve study, funding, and disclosure requirements for community associations. These changes are increasing the need for accurate HOA reserve funds accounting and condo reserve fund accounting to support compliance, long-term planning, and financial transparency.
| State & Association Type | Before | 2026 Change Requirement | Impact on HOA & Condo Accounting |
|---|---|---|---|
| Florida: Qualifying Residential Condom | Associations had greater flexibility around certain reserve funding decisions. | Condominiums in buildings 3+ habitable stories must follow SIRS requirements for specified structural components, with reserve funding aligned with the applicable SIRS funding plan. | Requires more accurate component-level reserve tracking, budgeting, and reconciliation. |
| Wahington: Community Associations | Reserve studies and periodic updates were already required for covered associations, with professional inspections at prescribed intervals. | Reserve studies generally require annual updates, with a professional visual inspection at least every 3 years, subject to statutory exceptions. | Reserve balances, replacement-cost estimates, and funding projections must be kept current in the accounting records. |
| Colorado: New Planned Communities & Condominiums | No comparable statewide requirement required developers of these new communities to establish an independent reserve-study baseline before turnover. | HB26-1099, effective August 12, 2026, requires the declarant of a new planned community or condominium to obtain an independent reserve study before transferring control. The study must project costs over 30 years. | Provides a formal starting point for reserve budgeting and gives accountants a long-term funding baseline. |
| Maryland: Covered HOAs & Condominiums | Reserve studies were already required for covered associations. | Reserve studies generally must be updated every 5 years, identifying component costs, useful lives, and recommended annual reserve funding. | Accounting records need to reflect updated component costs, remaining useful lives, expenditures, and recommended contributions. |
How New Reserve Laws Are Changing HOA and Condo Accounting
New reserve laws are making HOA and condo accounting more structured and compliance-focused. Associations now need to separate reserve funds, track costs by component, align budgets with legal requirements, maintain long-term forecasts, and strengthen reporting and documentation.
Separate Operating and Reserve Accounts
- Reserve funds should be kept separate from operating cash to ensure clear tracking and proper use
- Maintain a dedicated reserve account, often a money market account or CD
- Use separate ledger accounts for reserve activity
- Record monthly allocations as fund transfers, not expenses
- Never comingle reserve and operating funds
Component-Level Cost Tracking
- Reserve studies require detailed information on structural, mechanical, electrical, and plumbing components, including useful life and replacement costs
- Use sub-ledgers or tags for components such as roofs, elevators, facades, and pool equipment
- Track funding against each component’s target
- Monitor useful lives and replacement costs
- Flag components nearing replacement for budget prioritization
Updated Annual Budgets Tied to Statutory Minimums
- Reserve budgets must increasingly reflect state-specific requirements and deadlines.
- Florida requires full funding for the eight mandatory SIRS components beginning January 1, 2026: roof, load-bearing walls, fire protection, plumbing, electrical, waterproofing, windows, and exterior doors
- Michigan requires at least 10% of the annual budget to be allocated to reserves.
- Review budgets against state-specific requirements before adoption
- Document permitted waiver or reduction votes and maintain separate templates for different jurisdictions
Long-Term Repair and Replacement Forecasting
- Reserve studies provide a long-term plan for when major components need replacement and how much funding will be required
- Maintain 10–30-year forecast schedulesk
- Reforecast after each updated reserve study
- Florida requires SIRS updates at least every 10 years
- Compare budgeted contributions with actual funding and track variances year over year
Reporting and Disclosure Requirements
- Accurate reserve accounting is increasingly important for owner, buyer, and lender disclosures
- California requires a reserve summary in the annual report
- Maintain member-facing reserve reports and updated resale disclosure packets
- Keep lender-facing financials accurate and current
- In Florida, distinguish condominium/cooperative requirements under Chapter 718 from HOA rules under Chapter 720
Percent-Funded Calculations
- Reserve strength is measured not only by dollars held but also by how much of the required funding target has been met
- Reserves are generally expected to be 70%–100% funded, with 15%–40% of the annual budget allocated to reserves
- Use the formula: (Actual Reserve Balance) ÷ (Fully Funded Reserve Target per the Study) = Percent Funded
- Keep the current funding target updated with each reserve study
- Track figures used in resale disclosures and lender questionnaires
Interest Income Allocation and Tax Treatment
- Interest earned on reserve funds requires separate tracking and tax treatment
- Reserve contributions are capital contributions, while reserve interest is treated as non-exempt income
- The original content states a 30% federal rate under Form 1120-H
- Determine whether the association files Form 1120-H or Form 1120
- Use separate reserve asset and income accounts, including a dedicated line such as account 4510 for reserve interest
- Code interest separately at the transaction level
Improved Audit Trails and Documentation
- Reserve withdrawals require stronger approval and documentation to create a clear audit trail
- Many regulations require two board members to approve reserve withdrawals
- Retain email or e-signature approvals showing the amount, vendor, and supporting invoices
- Build approval workflows into bookkeeping
- Retain documentation for each transaction
- Link every reserve disbursement to its supporting invoice or proposal
Strengthen Reserve Fund Compliance with Expert Real Estate Accounting
As reserve fund laws become more demanding, HOA and condo associations need accurate reporting, disciplined fund tracking, and stronger long-term planning. Expert real estate accounting helps boards improve transparency, reduce compliance risks, and maintain reliable financial records while preparing more effectively for future repairs, replacements, and funding obligations.
Whiz Consulting provides specialized real estate accounting services for HOA and condo associations. Our team helps manage reserve fund accounting, reconciliations, budgets, financial reporting, and compliance-related documentation, giving boards clearer financial visibility and more confidence in their decisions.

Get customized plan that supports your growth
Have questions in mind? Find answers here...
No. Reserve study requirements vary by state and the association’s governing documents. Some states require reserve studies for certain HOA or condo associations, while others only recommend them. Associations should review their state laws and bylaws to understand their specific obligations.
The required frequency depends on state regulations. Some states require annual updates with periodic professional inspections, while others recommend updating reserve studies every three to five years. Regular updates help ensure funding plans reflect current repair costs and asset conditions.
Generally, no. Reserve funds are intended for major repairs and replacement of common assets such as roofs, elevators, roads, and HVAC systems. Using reserve funds for routine operating expenses may be restricted by state law or require board and homeowner approval.
Reserve contributions should be recorded separately from operating income and deposited into dedicated reserve accounts. Proper accounting ensures accurate financial reporting, maintains transparency, and helps associations track available funds for future capital projects.
An underfunded association may struggle to pay for major repairs when they become necessary. This can result in deferred maintenance, special assessments, higher homeowner contributions, loans, or reduced property values if reserve balances remain insufficient.
Thousands of business owners trust Whiz to manage their account
Let us take care of your books and make this financial year a good one.