

In This Blog Post
Share This Article
- Last Updated: Oct 16, 2026
- 🔊 Listen
TL;DR
- A startup bookkeeping checklist includes transaction recording, account reconciliation, payroll review, financial statements, and AP/AR review.
- Completing these tasks monthly helps founders monitor cash flow, assess burn rate and runway, and identify financial discrepancies early.
- Avoiding common bookkeeping errors and recording transactions correctly helps maintain reliable financial reports for business decisions and investor discussions.
- As financial transactions increase, outsourcing bookkeeping can help startups maintain accurate records, receive timely reports, and focus on business growth.
A well-defined startup bookkeeping checklist helps founders track transactions, reconcile bank accounts, review expenses, monitor cash flow, and keep financial records accurate.
As a startup founder, you’re already wearing multiple hats, be it, managing the operational side of things or the accounting part. While we may not be able to take everything off your plate, we can surely help you bring structure to your bookkeeping from day one.
That’s the whole objective of this blog: to help you manage your books better with a checklist that’ll support informed decision-making.

Keep Books Ready for Month-End
Get Tailored Bookkeeping Support for Your Startup
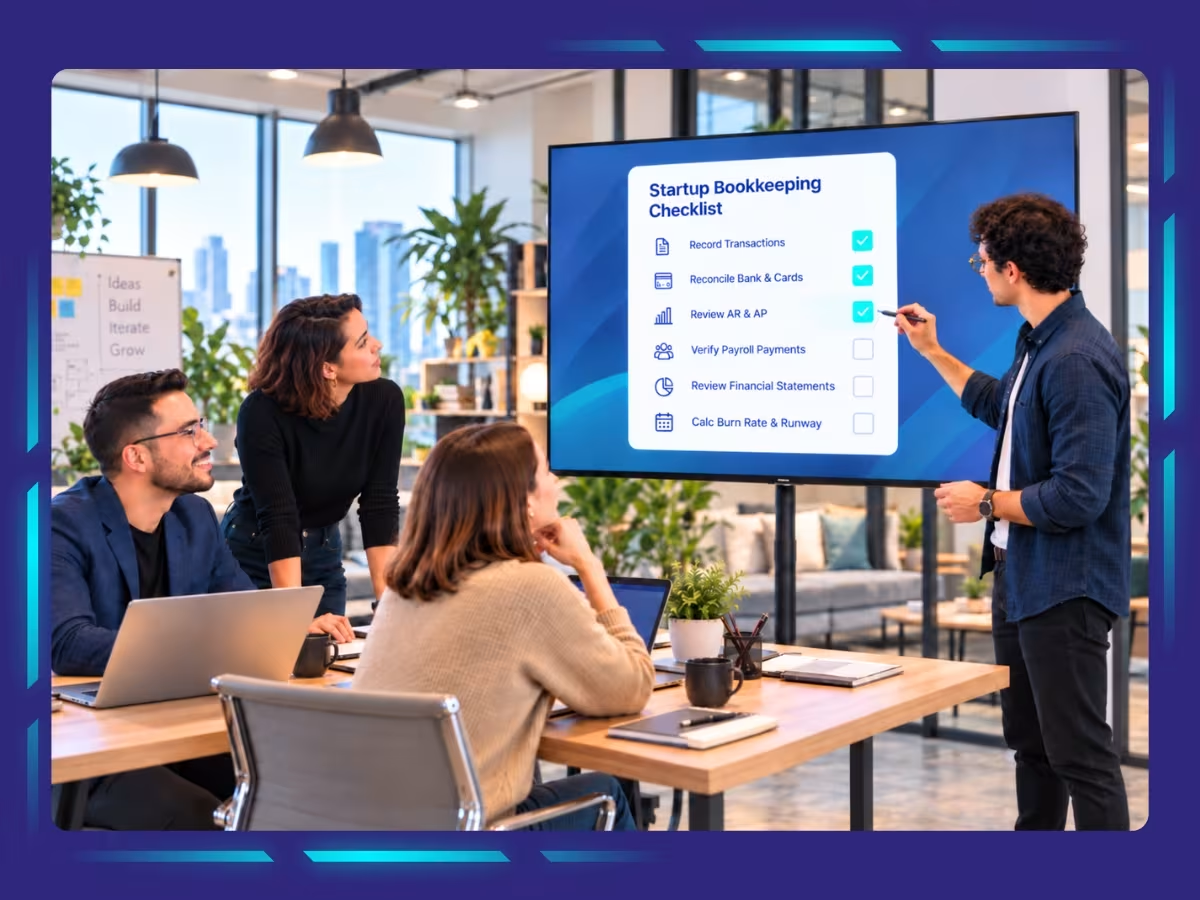
Monthly startup bookkeeping checklist: At a glance
| Bookkeeping Task | What to Check |
|---|---|
| Record and Categorize Transactions | Record all income and expenses, verify transaction categories, and check supporting documents. |
| Reconcile Bank and Credit Card Accounts | Match transactions with bank and credit card statements. Investigate missing, duplicate, or incorrect entries. |
| Review Accounts Payable | Check outstanding vendor bills, payment due dates, overdue balances, and upcoming cash requirements. |
| Review Accounts Receivable | Review unpaid invoices, check AR aging reports, and follow up on overdue customer payments. |
| Verify Payroll and Contractor Payments | Review wages, payroll deductions, tax withholdings, contractor payments, and W-9 records. |
| Review Financial Statements | Examine the profit and loss statement, balance sheet, and cash flow statement. Compare results with previous months. |
| Calculate Burn Rate and Runway | Calculate monthly cash burn and estimate how many months your available cash reserves will last. |
| Check Tax and State Filing Obligations | Review applicable federal, state, and local tax deadlines, payroll tax deposits, sales tax obligations, and required records. |
| Complete the Monthly Close | Verify adjustments, resolve discrepancies, review final financial statements, and close the accounting period. |
What should a monthly startup bookkeeping checklist include?
A monthly startup bookkeeping checklist should cover transaction categorization, account reconciliations, receivables and payables, payroll, financial statements, cash runway, tax obligations, and month-end closing. Completing these tasks helps US founders maintain reliable financial records, assess cash flow, and prepare financial information for funding discussions.
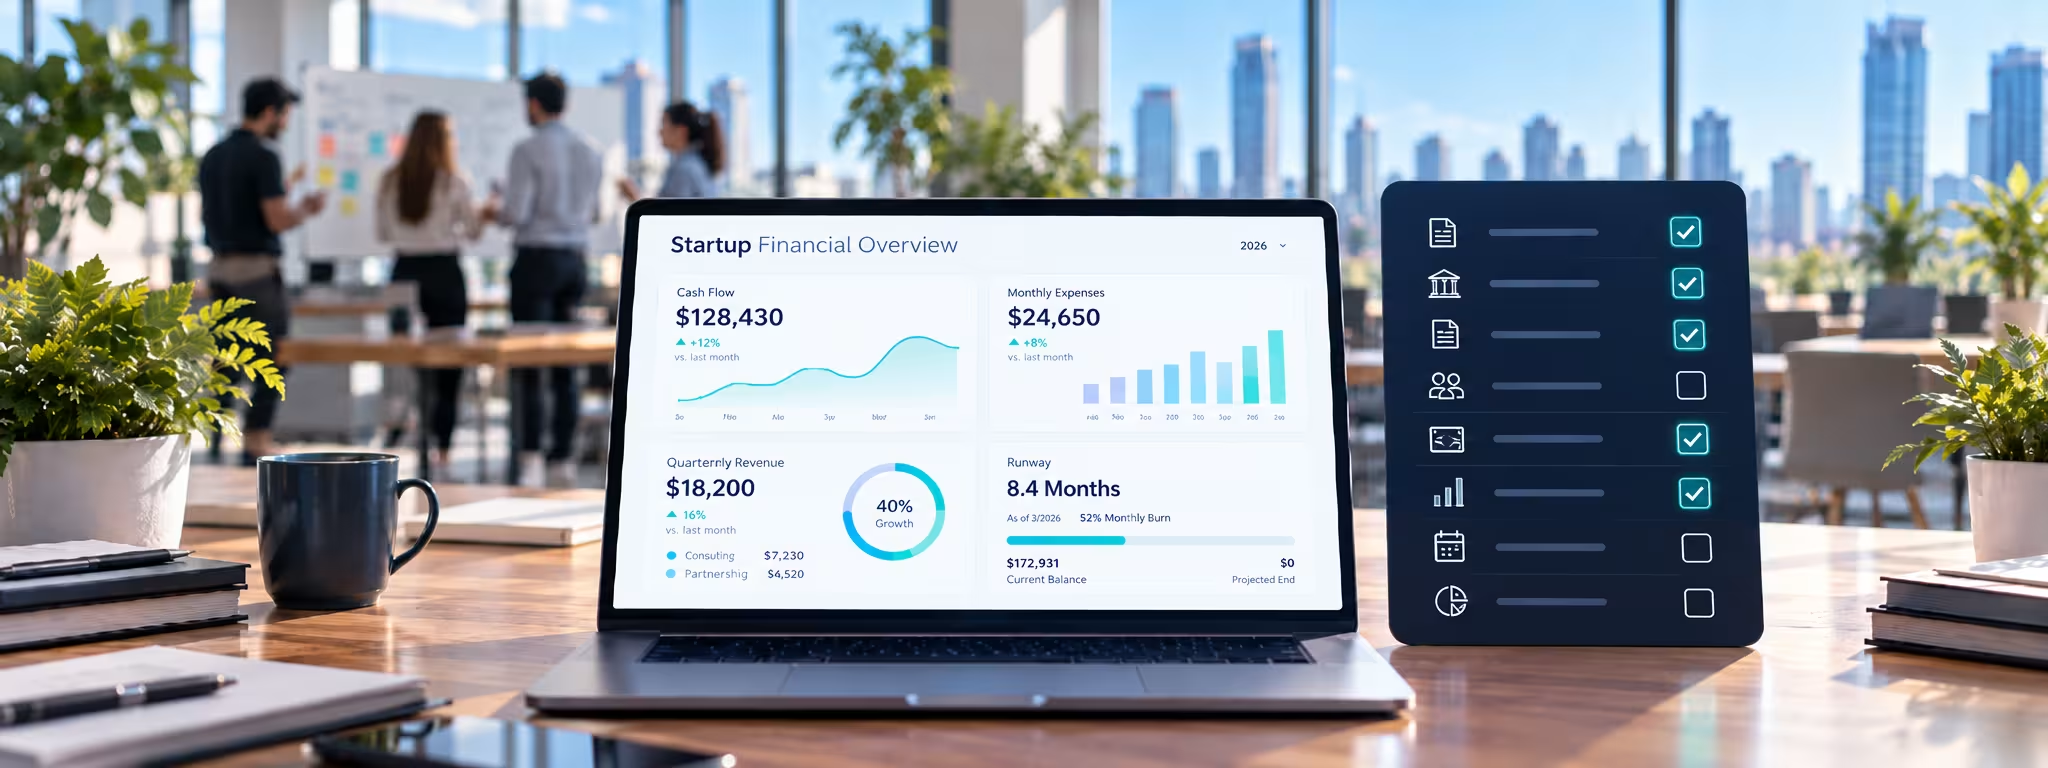
1. Record and categorize transactions
The first step is to gather all source documents in one place. Be it bank statements, vendor invoices, credit card bills, payroll records, or loan statements. If your accounting software automatically feeds transactions into the system through bank feeds, integrations, or AI-powered data entry, it reduces manual work. However, automatic data entry does not guarantee that every transaction is recorded correctly or classified accurately.
2. Reconcile bank and credit card accounts
The most important step of the startup bookkeeping checklist is reconciliation. It involves comparing your bank statement with transactions recorded by your accounting tool. You will be able to find any missing transactions, duplicate entries, unexpected bank feeds, and any other discrepancies that may affect your financial records.
The same process follows in credit card reconciliation. Review every credit card charge against its statement. If you find any variance, verify with an invoice or receipt and check the nature of the transaction.
3. Review accounts payable
As part of your monthly bookkeeping checklist, review outstanding invoices, terms of payment, and check due dates to identify overdue or upcoming payments. Keeping your payables record updated helps you to know about how much your business owes and when the money needs to go out.
As a startup founder, you may be working with a limited cash reserve; that is why this visibility is very useful. It will help you to prioritize payments, avoid late fees, and plan cash flow without disrupting day-to-day operations.
4. Review accounts receivable
Review your accounts receivable at the end of each month to track unpaid customer invoices and identify overdue payments. Check invoice due dates, review outstanding balances, and follow up with customers whose payments are past due. An accounts receivable aging report can help you prioritize collections by showing how long each invoice has remained unpaid.
For startups, timely follow-ups are particularly important because delayed customer payments can strain cash flow, even when sales are growing. Regularly reviewing receivables helps you estimate when money is likely to come in, address payment delays early, and make better decisions about upcoming business expenses.
5. Verify payroll and contractor payments
Review your monthly payroll to ensure employee wages, overtime, bonuses, and tax withholdings are calculated correctly. Check that federal and applicable state payroll taxes, Social Security and Medicare contributions, and benefit deductions are accurately recorded. Also, account for any changes in employee pay rates, hours worked, or paid time off.
For independent contractors, verify that payments match agreed rates, approved invoices, and completed work. Review contractor records to ensure the business has the necessary Form W-9 information and tracks payments that may require Form 1099-NEC reporting. These checks help prevent payment errors, support US payroll and tax compliance, and keep your monthly labor costs accurately reflected in your books.
6. Review monthly financial statements
Review your monthly profit and loss statement, balance sheet, and cash flow statement to understand how your startup is performing financially. The profit and loss statement shows your revenue, expenses, and profitability, while the balance sheet provides a snapshot of your assets, liabilities, and equity. The cash flow statement helps you track how money moves in and out of the business.
Compare these reports with previous months to spot changes in spending, revenue trends, growing liabilities, or potential cash flow issues. Regular reviews help you identify financial concerns early, assess whether your business is meeting its targets, and make informed decisions about budgeting, hiring, and future investments.
7. Calculate burn rate and runway
As a startup founder, you need to know how much cash your business uses each month and how long your available funds will last. Your monthly net burn rate is the difference between your cash outflows and cash inflows.
For example, if your startup spends $15,000 a month and receives $10,000 in cash, its net burn rate is $5,000 per month. If you have $50,000 in available cash, your runway is approximately 10 months at the current rate of spending.
Review these figures every month using your bank statements and cash flow records. Changes in payroll, software subscriptions, marketing expenses, customer payments, or other operating costs can affect how quickly your cash reserves decline.
8. Check tax and state filing obligations
Your startup’s tax obligations depend on its business structure, location, revenue, and employee count. So, make sure to review the federal, state, and local tax requirements that apply to your operations. This may include income tax returns, payroll tax deposits, and sales tax filings. Your filling requirements will further be differentiated based on your business type, be it, a sole proprietorship, partnership, LLC or corporation.
Keep track of filing deadlines and maintain income records, deductible expenses, payroll, and tax payments throughout the year. If your business operates across multiple states or sells taxable goods and services, check whether additional registration or filing requirements apply. Reviewing these obligations regularly helps prepare returns and avoid deadlines or potential penalties.
9. Complete the monthly close
At the end of each month, review your startup’s financial records to ensure transactions have been recorded in the correct period. This involves reconciling bank and credit card statements, checking outstanding invoices and bills, reviewing payroll entries, and verifying that expenses and revenue are accurately recorded. If your startup uses accounting software, make sure all relevant transactions have been entered and supporting documents are available for review.
Once these checks are complete, review your financial statements for unusual balances or discrepancies before finalizing the books. A consistent month-end close gives you a clearer picture of your startup’s financial position and ensures you have reliable figures to use when planning for the next month.
Which startup bookkeeping mistakes can distort financial reports?
Common startup bookkeeping mistakes include mixing personal and business expenses, misclassifying funding, overlooking accrued expenses, and skipping bank reconciliations. These errors can distort reported profits, cash balances, and liabilities, making it harder to assess financial performance and prepare reliable reports for investors.
- Mixing personal and business expenses: Use separate business accounts and credit cards for business and personal expenses. Record founder-paid business expenses as reimbursements or contributions, as appropriate, to maintain clear financial and tax records.
- Misclassifying expenses and funding: Distinguish operating expenses from capital expenditures, and never record investment proceeds as revenue
- Ignoring unpaid bills and accrued expenses: Record expenses in the correct accounting period, including costs incurred but not yet invoiced when accrual accounting applies
- Skipping bank reconciliation: Match every business bank and credit card account against its statements monthly. Investigate missing transactions, duplicate entries, and unexplained differences before closing the books.
- Miscalculating burn rate and runway: Calculate net burn consistently by accounting for operating cash outflows and inflows. Use current available cash to estimate runway, considering upcoming payments and expected changes in spending.
- Delaying professional support: If reconciliations remain incomplete, financial reports are consistently delayed, or bookkeeping takes time away from core business operations, consider whether your startup needs dedicated bookkeeping support.
Let our experts keep your books ready for every month-end close
Consistent bookkeeping helps you track spending, assess cash runway, and prepare reliable financial reports as your startup grows. At Whiz Consulting, our outsourced bookkeeping services support transaction recording, account reconciliation, expense categorization, and monthly reporting for startups and growing businesses in the US.
Need organized financial records and timely financial reporting support without hiring a full-time bookkeeping team? Let‘s connect!

Get customized plan that supports your growth
Have questions in mind? Find answers here...
A bookkeeping checklist for startups should cover transaction recording, expense categorization, reconciliation, AP/AR management, payroll, financial statement reviews, tax deadlines, and month-end adjustments.
Startups should record transactions regularly and reconcile accounts monthly. Reviewing cash balances, overdue invoices, and upcoming payments more frequently helps founders identify cash flow issues before they affect payroll, vendor payments, or operating plans.
Founders should review income statements, balance sheets, and cash flow statements every month. These reports show profitability, assets and liabilities, and cash movements, helping plan for business growth. Comparing results with previous months helps identify unusual expenses, declining revenue, and potential liquidity concerns.
Startups expecting to raise funding, manage inventory, or scale operations should generally use accrual accounting because it records revenue when it is earned and expenses when they are incurred. Cash accounting may suit very small startups with simple transactions, but eligibility, tax rules, and reporting requirements can also affect the choice.
Consider outsourcing when transaction volumes increase, reconciliations fall behind, financial reports arrive late, or you are spending too much time managing the books. External bookkeeping support can improve recordkeeping consistency and provide timely financial information without having to hire a full-time internal bookkeeper.
Thousands of business owners trust Whiz to manage their account
Let us take care of your books and make this financial year a good one.