

Real Estate
Financial Metrics in REIT: 5 Risk Factors Every CFO Should have on their Radar
Your real estate investment firm may have strong occupancy rates, steady rental income, and a portfolio of well-performing...
Read article 
Get the right real estate accounting support.
Your real estate investment firm may have strong occupancy rates, steady rental income, and a portfolio of well-performing properties, but that doesn’t necessarily mean your finances are in good shape. Rising borrowing costs, upcoming loan maturities, and increasing property expenses can put pressure on your returns, even when your overall performance looks healthy.
And that’s where looking at individual financial numbers can leave you with an incomplete picture. You need to understand how your property’s operating performance affects cash flow, whether your earnings can comfortably support your debt obligations, and how much room you have to fund future investments.
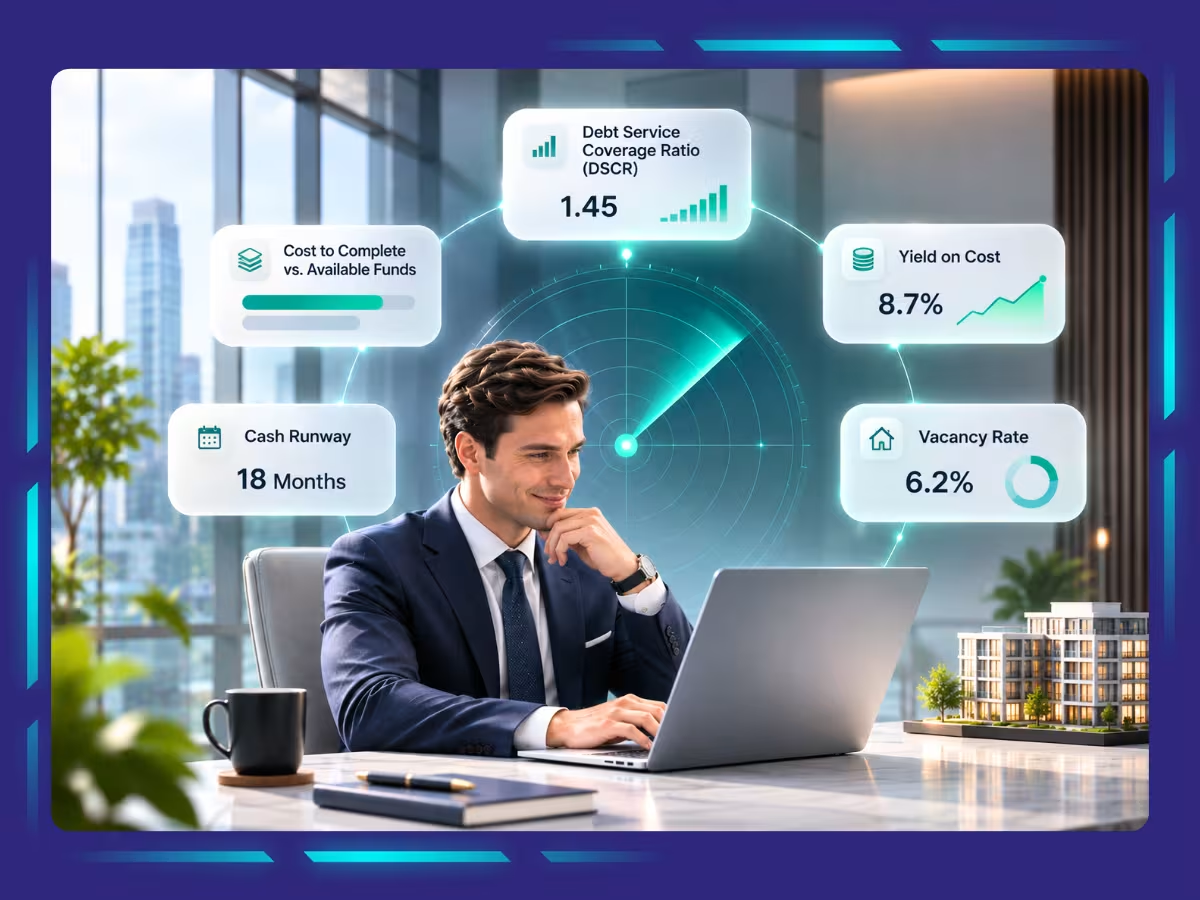
With so many financial metrics in REIT operations to review, the challenge is knowing which ones deserve your attention and what they reveal about your portfolio’s financial position. Here are five financial risk metrics you should be paying close attention to if you want a clearer picture of your REIT’s financial health and where your portfolio is headed.
| Metric | The question it answers | Formula | Benchmark | First move |
|---|---|---|---|---|
| Cash Runway | How many months can we operate before we need new money? | Unrestricted cash ÷ Average monthly net cash burn | Fewer months than the gap to your next maturity or committed spend | Pause discretionary capex or line up funding early |
| Cost to Complete vs. Available Funds | Can we finish what we’ve started? | Available funds − Estimated cost to complete | Below zero, or under 1.0x coverage (lenders may call the loan “out of balance”) | Re-estimate costs monthly and raise equity before the gap appears |
| Debt Service Coverage Ratio (DSCR) | Can this property’s income carry its loan, and how much cushion is left? | NOI ÷ Annual debt service | Within 0.10x of the covenant (lenders commonly require 1.20x to 1.25x) | Run it at refinancing rates before the loan comes up for renewal |
| Yield on Cost | Is this project still worth building at today’s costs? Also does the existing asset earn sufficient return on it? | (Annual NOI ÷ Total project cost) × 100 | Spread over market cap rate shrinking toward zero (developers typically target 1.0 to 2.0 points above) | Re-test the go/no-go decision whenever costs or rents move |
| Vacancy Rate | How much income is sitting empty, and is it getting worse? | (Vacant space ÷ Total rentable space) × 100 | Above your underwriting assumption or the submarket average | Look at lease expirations in the next 12 months, not just today’s number |
The five financial risk metrics you should monitor are Yield on Cost, Cost to Complete vs. Available Funds, Cash Runway, Debt Service Coverage Ratio (DSCR), and Vacancy Rate. Together, these financial metrics in REIT management help you assess whether your investments are delivering expected returns, whether you have enough funding to meet upcoming obligations, and where financial pressure may be building across your real estate portfolio.
Cash Runway measures how long your real estate investment company can cover its cash obligations using available liquidity before it needs additional funding. It’s particularly useful when you’re managing properties with negative cash flow, funding redevelopment projects, or dealing with temporary rental income disruptions.
Formula:
Cash Runway (Months) = Available Unrestricted Cash ÷ Average Monthly Net Cash Burn
Why it matters:
When rental income falls short of expectations, you still need to cover operating expenses, debt payments, and property maintenance costs. The pressure on your cash reserves can grow further if a major tenant vacates a property, or an unexpected repair adds to your expenses.
That’s why it is important that you track cash runway alongside your cash flow forecasts to help you understand how long your existing reserves can support your commitments. You can then decide whether to preserve cash, adjust capital spending, or secure additional funding before liquidity becomes a concern.
Cost to Complete vs. Available Funds measures whether your portfolio has enough money to finish an ongoing development or major renovation project. It compares your remaining project expenses with the funds you can access, including committed equity, available cash, and undrawn construction loans.
Formula:
Funding Surplus or Shortfall = Available Funds − Estimated Cost to Complete
Why it matters:
Construction costs can change throughout a project and push the budget over the limit with rising material prices, labor shortages, and unexpected delays. If you don’t update your cost estimates regularly, you may underestimate how much money you’ll need to finish the work.
By comparing your remaining expenses against available funding, you can identify potential shortfalls early and plan how to cover them. You can also assess whether additional funding will still make financial sense given the project’s expected returns.
Debt Service Coverage Ratio (DSCR) measures whether your property’s operating income can cover its debt obligations, including principal and interest payments. For your REIT, it helps you assess how comfortably your properties can service their debt without relying on additional cash reserves.
Formula:
DSCR = Net Operating Income (NOI) ÷ Total Annual Debt Service
Why it matters:
A DSCR above 1.0 indicates that your property’s operating income covers its debt payments, but the amount of breathing room matters just as much. If your DSCR sits at 1.10, even a modest decline in rental income could make it difficult to meet your obligations.
This becomes particularly important when your REIT faces higher interest rates or approaches a loan refinancing. Even if your property’s income remains steady, higher debt payments can reduce your coverage ratio and affect the financing terms lenders offer.
Yield on Cost (YoC) measures the annual Net Operating Income (NOI) a property generates relative to its total investment cost. For your portfolio, it’s particularly useful when evaluating development projects or major renovations, as it helps you determine whether the expected income justifies the capital invested.
Formula:
Yield on Cost (%) = (Annual NOI ÷ Total Project Cost) × 100
Why it matters:
The real value of this metric becomes clear when project costs or income expectations change. For example, if development costs increase to $23 million while projected NOI stays at $1.4 million, your yield falls from 7% to approximately 6.1%.
That difference matters when you decide whether to commit additional capital to a project. You can also compare your projected yield on cost with market capitalization rates for similar stabilized properties to assess whether developing the asset offers enough potential return to justify the additional time and risk.
Vacancy Rate measures the percentage of your property’s rentable space that remains unoccupied during a given period. For your property investment company, it helps you understand how much potential rental income you’re missing and whether tenant demand is keeping pace with your expectations.
Formula:
Vacancy Rate (%) = (Vacant Rentable Space ÷ Total Rentable Space) × 100
Why it matters:
A high vacancy rate means lost rental income, which can reduce your NOI and weaken debt coverage. The longer units remain vacant, the greater the financial impact. However, filling those units also comes with costs such as leasing commissions, property improvements, and rent concessions. This makes tenant retention just as important as finding new tenants quickly.
To manage these costs and protect your returns, monitor upcoming lease expirations, tenant retention, and local market conditions. These insights help you make timely pricing adjustments, improve leasing efforts, and keep vacancies under control.
A real estate CFO’s risk dashboard should give you a clear view of where financial pressure may be building across your portfolio. Beyond tracking individual property performance, it should highlight debt coverage, refinancing risks, available liquidity, and potential income losses. This helps you identify which properties need attention and where you may need to adjust your financial plans.
Your lender shouldn’t be the first person to notice a change in your DSCR, liquidity, or projected NOI. By the time a covenant issue appears in a quarterly report, your options to address it may already be limited. Identifying these risks early requires more than reviewing financial statements. It requires accurate, up-to-date accounting records and consistent monitoring of the financial metrics in REIT portfolios that influence property performance and financial stability.
This is where an experienced, dedicated accounting team can make a difference. By maintaining accurate property-level records, reconciling accounts, tracking debt obligations, and preparing timely financial reports, the team helps the CFO understand where financial pressure may be building. AI-backed workflows can further strengthen this process by automating routine reconciliations, identifying unusual transactions, and flagging potential inconsistencies for review. Together, accounting expertise and technology give your finance team more reliable information to assess risks, plan ahead, and make informed decisions before financial challenges become harder to manage.

Get customized plan that supports your growth
The five key financial metrics for REITs are Cash Runway, Cost to Complete vs. Available Funds, Debt Service Coverage Ratio (DSCR), Yield on Cost, and Vacancy Rate. These metrics help CFOs evaluate liquidity, debt obligations, investment returns, development funding, and potential rental income losses.
CFOs can identify financial risks by regularly reviewing property-level cash flows, debt coverage, loan maturities, occupancy trends, and projected operating income. Comparing current performance against forecasts and lender requirements helps identify potential financial pressures before they affect portfolio stability.
A DSCR above 1.0 indicates that a property’s net operating income covers its debt obligations. However, many commercial real estate lenders require a DSCR of approximately 1.20x to 1.25x or higher, depending on the property type, loan structure, and lending conditions.
A higher vacancy rate reduces potential rental income and can weaken a property’s Net Operating Income (NOI). Prolonged vacancies may also increase leasing expenses and reduce debt coverage. Monitoring vacancy trends, lease expirations, and tenant retention helps REITs manage these financial risks.
A portfolio’s financial risk dashboard should include stressed DSCR, debt yield, upcoming loan maturities, refinancing gaps, liquidity coverage, and projected NOI at risk. Tracking these indicators together helps CFOs assess financial exposure across properties and identify where corrective action may be necessary.
AI-backed accounting workflows can automate transaction categorisation, support reconciliations, identify unusual financial activity, and flag reporting inconsistencies. Combined with experienced accounting professionals, these capabilities help REIT finance teams maintain accurate financial records, monitor changing conditions, and make more informed financial decisions.
Let us take care of your books and make this financial year a good one.
Your real estate investment firm may have strong occupancy rates, steady rental income, and a portfolio of well-performing...
Read article
Accounts payable (AP) teams implement vendor fraud prevention by enforcing strict internal controls, like three-way invoice matching, independent...
Read article
US healthcare providers analyze their balance sheets, income statements, and cash flow reports by tracking key performance indicators...
Read article