

Table of Content
Share This Article
- Last Updated: Oct 22, 2026
- 🔊 Listen
TL;DR
- Invoice financing helps Australian businesses access cash tied up in unpaid customer invoices sooner.
- Providers may advance around 80% to 90% of an eligible invoice, depending on the facility.
- Common options include invoice factoring, invoice discounting, selective financing, and confidential financing.
- Invoice financing costs depend on fees, customer risk, payment terms, and the type of arrangement.
- Faster access to receivables can support payroll, supplier payments, and short-term working capital needs.
- Businesses should weigh financing costs against the cash flow benefits before using the facility regularly.
- Accurate accounting is essential for recording advances, fees, customer payments, and outstanding balances correctly.
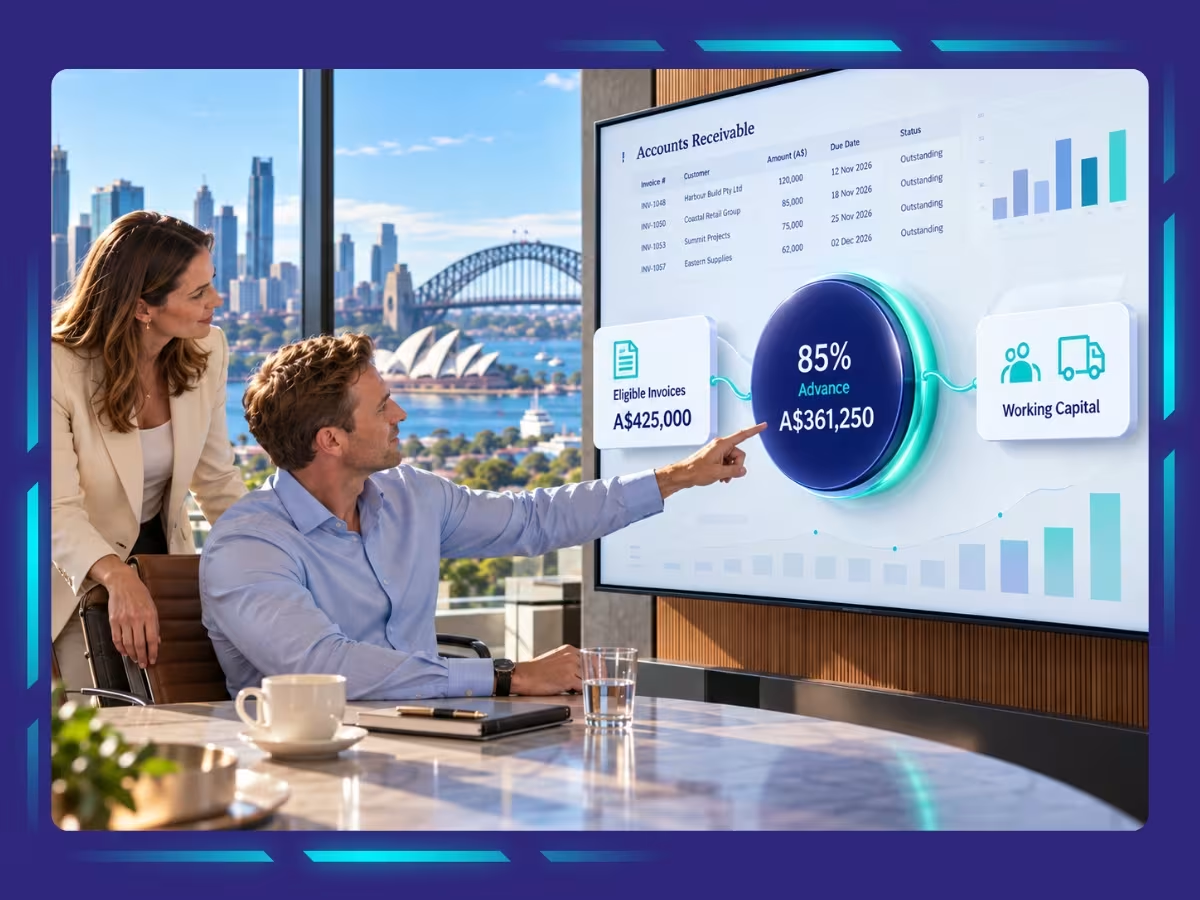
Invoice financing in Australia allows businesses to tap into cash tied up in unpaid invoices. A lender advances around 80%-90% of the invoice value upfront. The remaining balance follows once your client pays.
Waiting 30, 60, or even 90 days for clients to settle invoices can put a serious handbrake on your business growth. When cash is tied up in outstanding receivables, covering payroll, purchasing inventory, or taking on new contracts becomes an uphill battle. This step-by-step guide breaks down how invoice financing works in Australia. It compares factoring and discounting options, costs, and key strategies to keep your working capital flowing smoothly.
Improve Visibility Across Your Receivables
Track invoices, payments, and financing costs with greater clarity.
What is invoice financing?
Invoice financing is a type of business funding that allows companies to access cash tied up in unpaid customer invoices. Instead of waiting 30, 60, or even 90 days for customers to pay, a business can receive an advance from a finance provider based on the value of eligible invoices.
This can be particularly useful when customer payments are slow. According to the Payment Times Reporting Regulator, large businesses report an average common payment term of 29 days. However, it takes them an average of 55 days to pay 95% of their small business invoices.
Invoice financing helps bridge that gap by converting outstanding receivables into working capital sooner. Once the customer pays, the finance provider releases the remaining balance after deducting its fees and charges.
For Australian businesses, this can help cover payroll, supplier payments, and other operating costs without waiting for every invoice to clear.
What are the main types of invoice financing?
The main types of invoice financing are invoice factoring, invoice discounting, selective invoice financing, and confidential invoice financing. They mainly differ in who manages collections, which invoices are funded, and whether customers know financing is being used:
Invoice Factoring
With invoice factoring, the finance provider advances funds against unpaid invoices and usually takes responsibility for collecting payment from customers. Because the provider is involved in debtor management, customers are generally aware that the invoices have been financed.
Invoice Discounting
Invoice discounting allows a business to borrow against its outstanding invoices while continuing to manage customer relationships and collections itself. This option is often preferred by businesses that already have a strong internal accounts receivable process.
Selective Invoice Financing
Selective invoice financing allows businesses to choose specific invoices to finance rather than committing their entire receivables ledger. It can be useful when extra working capital is needed occasionally rather than on an ongoing basis.
Confidential Invoice Financing
With confidential invoice financing, the funding arrangement is not disclosed to customers. The business continues to issue invoices and collect payments under its own name while receiving funding against eligible receivables.
How does invoice financing work step-by-step?
Invoice financing works by turning unpaid customer invoices into earlier access to cash. The process involves issuing the invoice, submitting it for funding, receiving an advance, collecting payment, and receiving the remaining balance for less fees. The process usually follows five main steps:

- Step 1: Issue an Invoice to Your Customer: The business provides goods or services and sends the customer an invoice with agreed payment terms, such as 30 or 60 days.
- Step 2: Submit the Invoice to the Finance Provider: The eligible invoice is submitted to the invoice finance provider for approval. The provider may assess factors such as the invoice value, payment terms, and the customer’s creditworthiness.
- Step 3: Receive an Advance Against the Invoice: Once approved, the provider advances a percentage of the invoice value to the business. This gives the business earlier access to cash that would otherwise remain tied up in accounts receivable.
- Step 4: The Customer Pays the Invoice: When the invoice becomes due, the customer makes payment. Depending on the financing arrangement, the payment may go directly to the finance provider or through a designated account.
- Step 5: Receive the Remaining Balance Less Fees: After receiving the customer payment, the finance provider deducts its agreed fees and charges and releases the remaining invoice balance to the business.
This allows Australian businesses to convert outstanding invoices into working capital sooner rather than waiting until the end of the customers payment term.
How Much Does Invoice Financing Cost in Australia?
The cost of invoice financing in Australia varies by provider, invoice value, customer risk, payment terms, and the type of facility used. Most providers charge a service or facility fee. Some also apply a financing or discount charge, based on the amount advanced and how long the invoice remains unpaid.
Service fees could range from around 1.5% to 4.5% of the invoice value, although the total cost may be higher depending on the arrangement.
Australian providers may offer anywhere from roughly 80% to 90% of eligible invoice value, with the remaining balance released after the customer pays, less applicable fees. The final cost usually depends on:
- Invoice value and volume: Larger or more frequent invoices may qualify for different pricing
- Customer creditworthiness: Higher-risk debtors can increase financing costs
- Payment terms: Longer customer payment periods can increase charges where fees accrue over time
- Type of facility: Factoring may cost more than invoice discounting because it can include collections and debtor management
- Additional charges: Some providers may apply establishment, administration, minimum-use, or account-management fees
What are the benefits of invoice financing?
Invoice financing can help Australian businesses access cash sooner, improve working capital, and reduce the pressure caused by long customer payment terms. By releasing funds tied up in unpaid invoices, it gives businesses more flexibility to manage day-to-day costs and plan ahead. Here’s what it includes:
- Faster Access to Cash: Businesses can unlock funds tied up in unpaid invoices instead of waiting for customers to pay.
- Improved Working Capital: Earlier access to receivables can help cover payroll, supplier payments, and everyday operating costs.
- Funding Can Grow with Sales: As invoice values increase, the amount of available finance may also increase, depending on the facility.
- Less Reliance on Traditional Loans: Invoice financing is based largely on receivables, which can provide an alternative to conventional borrowing.
- More Predictable Cash Flow: Receiving funds earlier can make it easier to plan expenses and manage short-term cash requirements.
What accounting treatment does invoice finance require?
Invoice finance accounting involves recording the advance, financing fees, customer payments, and regular reconciliations correctly. Whether the receivable stays on the balance sheet depend on the structure of the arrangement and the transfer of risk.
Record the Initial Advanced
When funding is received against an invoice, the business records the cash received. If it retains the underlying receivable and repayment risk, the advance is generally recorded as a financing liability rather than revenue.
Account for fees and charges
Service fees, discount charges, and other financing costs should be recorded separately from the original sales revenue. Correct classification helps businesses see the true cost of using invoice finance and its effect on profitability.
Record customer payments
When the customer pays, the receivable is cleared from the accounts. Any amount retained by the finance provider should also be recorded. This covers repayment of the advance and fees, so the funding balance is reduced correctly.
Assess whether receivable should be derecognised
The treatment becomes more complex when invoices are sold or factored. Whether the receivable can be removed from the balance sheet depends on the transfer of risk. It turns on whether the business has transferred substantially all the risks and rewards of ownership under the applicable accounting standards.
Reconcile invoice finance accounts regularly
Businesses should reconcile funded invoices, customer receipts, provider statements, financing liabilities, and fees regularly. This helps identify missing payments, incorrect charges, or outstanding balances before they affect month-end reporting.
Improve cash flow visibility with expert invoice processing services
Invoice financing can help Australian businesses access cash sooner. However, its value depends on accurate invoicing, reliable receivables tracking, and clear visibility into customer payments and financing costs. Strong accounting processes help businesses monitor outstanding invoices, reconcile funded receivables, assess the true cost of financing, and make better working-capital decisions.
At Whiz Consulting, our invoice processing services help businesses maintain accurate invoice records, track receivables, reconcile payments, and improve cash flow visibility. With organised financial data and timely reporting, you can manage invoice financing more effectively while keeping day-to-day cash flow under control.

Get customized plan that supports your growth

Have questions in mind? Find answers here...
Once the facility is approved and established, eligible invoices can often be funded within 24 to 48 hours. The exact timing depends on the provider, invoice verification, and facility terms.
Invoice financing is the broader funding method of borrowing against unpaid invoices. Invoice factoring is a type of invoice finance where the provider typically manages customer collections, while invoice discounting generally allows the business to retain control of its sales ledger and collections.
Yes, it can suit small B2B businesses that issue invoices on credit terms and experience cash flow gaps while waiting for payment. Eligibility usually depends on factors such as invoice quality, trading history, and the creditworthiness of customers.
They may be. Interest and certain borrowing costs incurred for business or income-producing purposes can generally qualify for tax deductions, but the treatment depends on the type of fee and financing arrangement. Some borrowing expenses may need to be deducted over several years rather than immediately, so businesses should confirm the treatment with a registered tax professional.
This depends on whether the arrangement is recourse or non-recourse. Under recourse financing, the business may remain responsible for the unpaid invoice. Businesses should review their facility agreement carefully and monitor customer credit risk before financing receivables.
Applying for invoice finance may involve a credit enquiry, and credit applications can affect a credit report or score. However, invoice finance providers also place significant emphasis on the quality of the business’s receivables and customers, rather than relying solely on the business’s own credit profile.
Thousands of business owners trust Whiz to manage their account
Let us take care of your books and make this financial year a good one.