

Table of Content
Share This Article
- Last Updated: Sep 29, 2026
- 🔊 Listen
TL;DR
- A well-structured chart of accounts helps Australian small businesses maintain accurate and organised financial records.
- The five core account categories are assets, liabilities, equity, revenue, and expenses.
- Setting up a COA requires appropriate account codes, clear categories, and accurate GST settings.
- Correct account classification and GST coding simplify BAS preparation and reduce potential reporting errors.
- Accounting software like Xero, MYOB, and QuickBooks help businesses organise and manage their accounts.
- Regular COA reviews help identify duplicate accounts, outdated categories, and incorrect transaction classifications.
A chart of accounts is the foundation of organised bookkeeping, helping Australian small businesses categorise transactions, track income and expenses, and prepare accurate financial reports. A well-structured chart of accounts also makes GST tracking and BAS preparation easier while providing clearer visibility into business performance. However, choosing the right account categories, setting up GST codes, and maintaining a consistent structure can be challenging. This guide explains the five main types of accounts, how to set up a chart of accounts for your Australian small business, common mistakes to avoid, and best practices for keeping your financial records organised as your business grows.
Make Your Chart of Accounts Easier
Keep your books organised, GST accurate, and BAS preparation on track.
What Is a Chart of Accounts, and Why Does It Matter?
A chart of accounts (COA) is an organised list of all the financial accounts a business uses to record and categorise its transactions. It groups accounts into five main categories: assets, liabilities, equity, revenue, and expenses. For Australian small businesses, a well-structured chart of accounts supports accurate bookkeeping, financial reporting, and GST and BAS preparation. Here’s why it matters:
- Organised Financial Records: Keeps business transactions consistently categorised, making bookkeeping and reconciliation easier.
- Accurate Financial Reporting: Helps prepare reliable profit and loss statements, balance sheets, and other financial reports.
- Simplified GST and BAS Preparation: Supports accurate GST tracking and transaction classification when accounts are configured with the correct tax codes.
- Better Financial Visibility: Makes it easier to monitor income, expenses, profitability, and overall business performance.
- Informed Business Decisions: Provides structured financial information to support budgeting, cash flow planning, and business growth.
What Are the Core Categories in a Chart of Accounts?
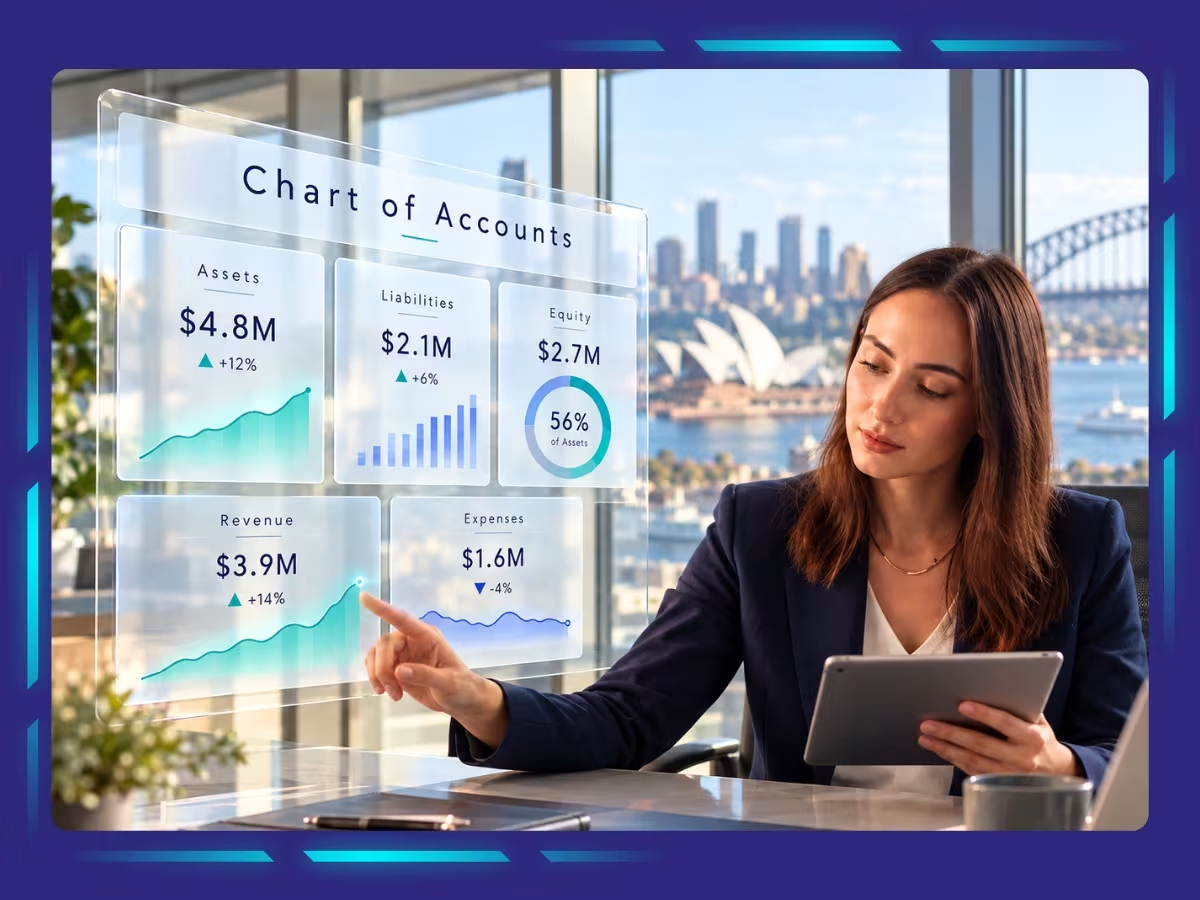
A chart of accounts is divided into five main categories: assets, liabilities, equity, revenue, and expenses. Each category helps Australian small businesses classify transactions, maintain accurate financial records, and prepare financial statements. Understanding these categories also makes it easier to structure accounts for GST tracking and BAS preparation.
Assets
Assets are resources a business owns or controls that provide current or future economic benefits. They include current assets, such as cash, accounts receivable, inventory, and prepaid expenses, as well as non-current assets, such as property, vehicles, and equipment.
Liabilities
Liabilities represent amounts a business owes to suppliers, employees, lenders, and government authorities. Common liability accounts include accounts payable, business loans, accrued expenses, GST payable, PAYG withholding, and superannuation payable. These accounts help Australian businesses monitor outstanding obligations and plan upcoming payments.
Equity
Equity represents the owner’s or shareholders’ interest in the business after deducting liabilities from assets. Depending on the business structure, equity accounts may include owner’s capital, drawings, share capital, and retained earnings.
Revenue
Revenue represents income generated through a business’s primary operations, such as selling products or providing services. Revenue accounts may include product sales, consulting fees, subscription income, and service revenue.
Expenses
Expenses are the costs incurred to operate a business and generate revenue. They include direct costs, such as the cost of goods sold, and operating expenses, such as wages, rent, utilities, insurance, advertising, and software subscriptions.
How to Set Up a Chart of Accounts for Your Australian Small Business
Setting up a chart of accounts involves organising your business’s financial accounts into a structure that supports accurate bookkeeping, financial reporting, and GST compliance. The following six steps will help Australian small businesses create a chart of accounts that meets their current accounting needs and can accommodate future growth.
Step 1: Identify Your Business’s Accounting Needs
Start by reviewing your business structure, industry, revenue streams, and regular expenses. A retail business, for example, may need separate accounts for inventory, cost of goods sold, and shipping, while a consulting firm may require accounts for different service revenues and professional expenses. Also consider your reporting needs, GST registration status, and whether you need to track individual departments, projects, or locations.
Step 2: Choose the Right Account Categories and Codes
Organise your chart of accounts into the five main categories: assets, liabilities, equity, revenue, and expenses. Assign unique account codes to create a logical structure that makes transactions easier to classify, and financial reports easier to navigate. For example, you might use the 1000 series for assets, 2000 for liabilities, and 4000 for revenue. Leave gaps between account codes so you can add new accounts as your business grows.
Step 3: Create Accounts for Income, Expenses, Assets and Liabilities
Create individual accounts within each category based on your business’s actual transactions. These may include sales revenue, service income, wages, rent, accounts receivable, inventory, business loans, and GST payable. Keep accounts specific enough to provide useful financial information without creating unnecessary complexity. For instance, a business offering multiple services may benefit from separate revenue accounts to monitor each service’s performance.
Step 4: Configure GST Codes and BAS Reporting
If your business is registered for GST, configure the appropriate tax codes in your accounting software. Ensure transactions are classified correctly as taxable, GST-free, input-taxed, or outside the scope of GST, as applicable. Set up accounts to track GST collected and GST paid, and check that your tax settings support accurate BAS preparation. The ATO recommends maintaining accounting records that distinguish different GST treatments and support the amounts reported on your BAS.
Step 5: Set Up Your Chart of Accounts in Accounting Software
Enter your chart of accounts into accounting software such as Xero, MYOB, or QuickBooks, or customise the software’s existing account structure. Assign account names, codes, categories, and default tax settings where appropriate. If you are migrating from another system, map your existing accounts carefully to avoid duplicate accounts, missing balances, or incorrect transaction classifications.
Step 6: Review and Test Your Account Structure
Before using your new chart of accounts, review the account categories, descriptions, codes, and GST settings for accuracy. Test the structure using typical business transactions, such as customer invoices, supplier bills, payroll expenses, and asset purchases. Generate a sample profit and loss statement, balance sheet, and applicable GST reports to confirm that transactions appear in the correct categories. Review the structure periodically as your business introduces new products, services, or reporting requirements.
How Does Your Chart of Accounts Affect GST and BAS Reporting?
Your chart of accounts (COA) affects GST and BAS reporting by determining how financial transactions are classified and organised. When combined with correctly configured GST codes, a well-structured COA helps Australian small businesses track GST accurately, reduce reporting errors, and prepare their Business Activity Statements more efficiently.
- Accurate GST Classification: A well-organised COA, together with appropriate tax codes, helps distinguish taxable, GST-free, input-taxed, and other transactions. This reduces incorrect GST calculations and claims.
- Correct GST Tracking: Separate GST collected and GST paid accounts help businesses monitor their GST liabilities and eligible input tax credits. These records support accurate reconciliation before BAS lodgement.
- Simplified BAS Preparation: Correctly classified transactions allow accounting software to generate GST reports and calculate amounts for relevant BAS labels. Under Simpler BAS, eligible small businesses report total sales (G1), GST on sales (1A), and GST on purchases (1B).
- Fewer Reporting Errors: Consistent account classifications and GST codes make it easier to identify incorrectly coded purchases, missing transactions, and discrepancies before lodging your BAS.
- Easier Reconciliation and Record-Keeping: A structured COA helps businesses reconcile GST accounts with supporting invoices and transaction records, maintaining a clear audit trail, and resolving differences between accounting records and BAS reports.
Best Practices for Maintaining an Accurate Chart of Accounts
Maintaining an accurate chart of accounts requires regular reviews, consistent transaction categorisation, and a structure that adapts as your business grows. For Australian small businesses, following these best practices helps improve bookkeeping accuracy, simplify GST and BAS reporting, and maintain reliable financial records.
Keep Account Names and Codes Consistent
Use clear, descriptive account names and a logical numbering system. Apply consistent naming conventions to prevent confusion and ensure transactions are recorded in the correct accounts.
Review Your Chart of Accounts Regularly
Review your COA periodically to identify outdated, duplicate, or incorrectly classified accounts. Regular reviews help maintain accurate financial records and prevent unnecessary complexity.
Use Subaccounts Where Necessary
Create subaccounts to track specific revenue streams, expense categories, departments, or business activities. Avoid adding excessive detail that makes bookkeeping and financial reporting harder to manage.
Maintain Accurate GST Codes
Check that accounts have appropriate default GST codes, and that individual transactions receive the correct tax treatment. Review these settings whenever your business activities or GST requirements change.
Align Your COA with Financial Reporting Needs
Structure accounts provide meaningful information for profit and loss statements, balance sheets, budgeting, and cash flow analysis. This makes it easier to monitor financial performance and identify areas requiring attention.
Update Your COA as Your Business Grows
Add or modify accounts when introducing new products, services, locations, or revenue streams. Document significant changes and review their impact on existing financial reports to maintain reporting consistency.
Streamline Your Chart of Accounts with Expert Accounting Outsourcing Services
A well-structured chart of accounts is essential for accurate bookkeeping, reliable financial reporting, and efficient GST and BAS preparation. By organising accounts into the right categories, applying consistent codes, and reviewing the structure regularly, Australian small businesses can gain better visibility into their finances and make informed decisions as they grow.
At Whiz Consulting, our accounting outsourcing services help Australian businesses set up, organise, and maintain an accurate chart of accounts. From account categorisation and GST coding to bookkeeping, reconciliations, and financial reporting, our experienced accountants help keep your financial records consistent and up to date. With your accounting processes in capable hands, you can spend less time managing your books and more time growing your business.

Get customized plan that supports your growth

Have questions in mind? Find answers here...
No, there is no single mandatory chart of accounts for all Australian businesses. Small businesses can customise their accounts according to their industry, business structure, and reporting needs. Australia also has a National Standard Chart of Accounts, primarily designed for charities and not-for-profit organisations.
There is no fixed number of accounts a small business should maintain. The ideal number depends on its size, industry, transaction volume, and reporting requirements. A chart of accounts should provide enough detail to track financial performance without creating unnecessary complexity.
A well-structured chart of accounts helps businesses categorise transactions and track GST collected and paid. Combined with accurate GST codes, it supports BAS preparation, including reporting total sales (G1), GST on sales (1A), and GST on purchases (1B) under Simpler BAS.
Yes. Both Xero and MYOB allow businesses to customise their chart of accounts by adding, editing, or deactivating accounts. You can adjust account names, codes, categories, and applicable tax settings to suit your business and financial reporting requirements.
Review your chart of accounts at least annually, with additional checks during quarterly or monthly financial reviews. Update it whenever your business introduces new products, revenue streams, or significant expenses. Regular reviews help identify duplicate accounts, incorrect classifications, and outdated GST settings.
Thousands of business owners trust Whiz to manage their account
Let us take care of your books and make this financial year a good one.