

Table of Content
Share This Article
- Last Updated: Sep 29, 2026
- 🔊 Listen
TL;DR
- AI in accounting goes beyond basic automation by analysing financial data and identifying patterns.
- Indian finance teams are adopting AI to manage growing transaction volumes and reporting demands.
- AI streamlines invoice processing, bank reconciliation, expense categorisation, financial forecasting and audit preparation.
- AI-assisted GST and TDS checks help identify discrepancies while maintaining essential human oversight.
- Finance teams can measure AI ROI through time savings, reduced errors and lower processing costs.
AI in accounting goes beyond basic automation by analysing financial data, identifying patterns, and supporting smarter financial decisions. For Indian finance teams, growing transaction volumes and the need for faster, more accurate reporting are making AI increasingly relevant. From invoice processing and reconciliations to financial analysis, AI offers practical ways to reduce manual work and improve efficiency.
But where should finance teams begin, and how can they measure the results? This guide explores why adoption of AI in accounting and finance is accelerating in India, its practical applications and benefits, how to implement it in accounting workflows, and how to measure its return on investment.
Build a Smarter Workflow
Reduce Repetitive Work with AI-Powered Accounting Support
What is AI in Accounting, and How Is It Different from Basic Automation?
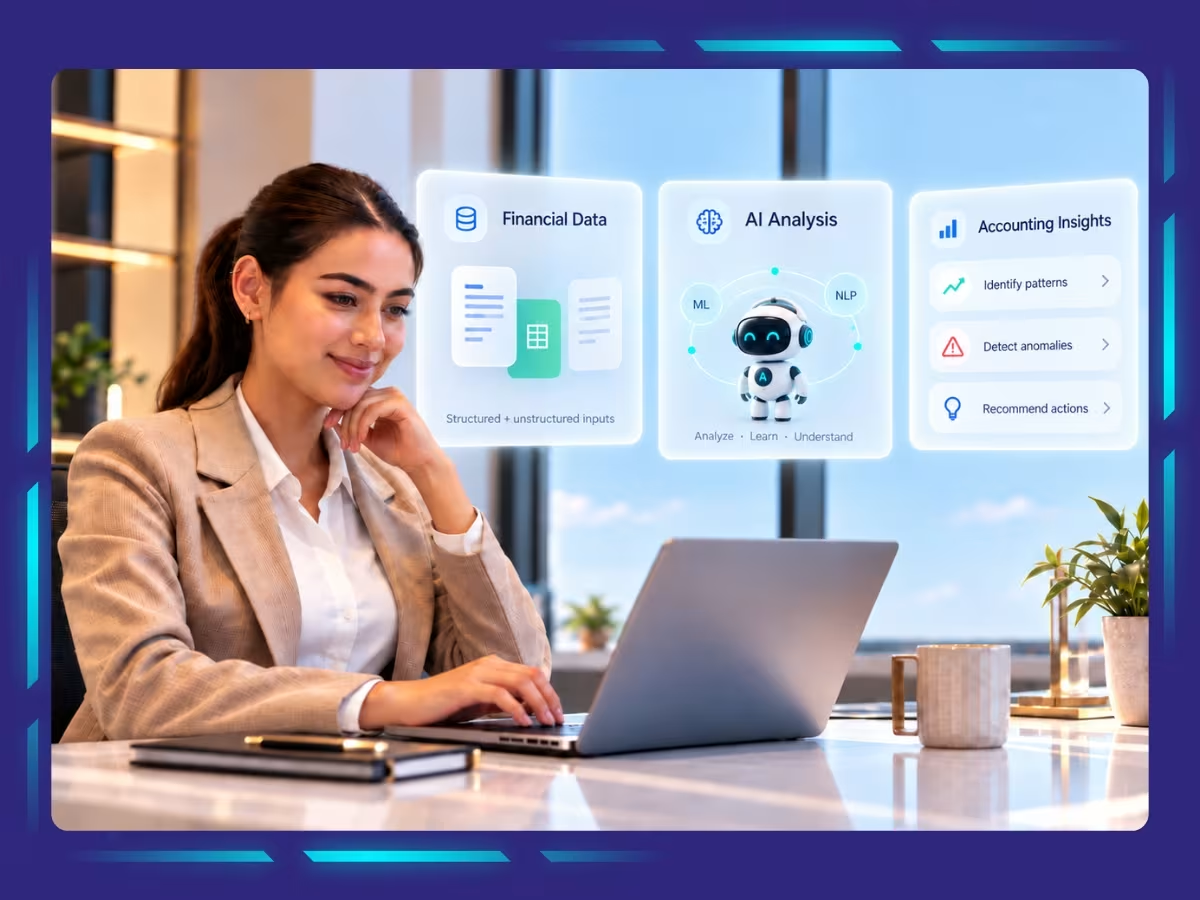
AI in accounting refers to using artificial intelligence to process financial information, automate accounting tasks, identify errors, and support financial analysis. For example, AI can extract invoice details, suggest transaction categories, flag unusual payments, and analyse historical data to support cash flow forecasts.
While basic automation follows predefined rules to complete repetitive tasks, AI can analyse patterns, interpret new information, and suggest actions based on financial data. Here’s how they differ:
| Basic Automation | AI in Accounting |
|---|---|
| Follows predefined rules and instructions |
Analyses data and identifies patterns |
| Handles repetitive, structured accounting tasks |
Can process complex and unstructured financial information |
| Requires manual intervention when transactions fall outside established rules |
Can flag unusual transactions and suggest appropriate classifications |
| Produces outputs based on fixed workflows |
Supports forecasting, anomaly detection, and financial analysis |
For example, basic automation can transfer invoice details into accounting software using predefined rules. AI can go further by suggesting expense categories, identifying potential duplicate invoices, and flagging unusual amounts for review.
For Indian finance teams, combining AI with traditional automation can streamline invoice processing, bank reconciliation, and financial reporting while keeping accountants responsible for reviewing financial information and compliance-related decisions. This is what makes AI for accountants practical rather than replacements for them: it takes on the repetitive first pass so accountants can focus their judgement on the exceptions and the decisions that actually need it.
Why Is AI Adoption Accelerating Among Indian Finance Teams Right Now?
Adoption of AI in accounting is accelerating among Indian finance teams as growing transaction volumes, digital compliance requirements, and demand for faster financial insights put pressure on traditional accounting processes. Businesses are increasingly exploring AI to handle routine work while enabling finance professionals to focus on analysis and strategic decisions, part of a broader shift toward AI in accounting and finance across Indian businesses more generally. Several factors are driving this shift:
- Rapid Growth in Digital Transactions: India’s expanding digital payments ecosystem is generating larger volumes of financial data. UPI alone processed approximately 24.5 billion transactions in August 2026, highlighting the scale of the country’s digital economy.
- Increasing Digital Compliance Requirements: GST e-invoicing and other digital reporting requirements demand timely, accurate financial records. AI can assist with invoice validation, discrepancy detection, and preparing records for compliance reviews, with human verification remaining essential.
- Pressure to Improve Productivity: Finance teams are expected to process transactions, complete reconciliations, and deliver reports without proportionately increasing manual workloads. AI offers opportunities to automate repetitive activities and redirect employees toward higher-value work.
- Growing Demand for Strategic Financial Insights: Finance leaders are moving beyond historical reporting toward forecasting and business decision support. Grant Thornton Bharat’s 2026 survey found that 62% of surveyed finance leaders identified strategic planning and decision support among their top three priorities.
- Greater Investment in AI and Digital Skills: Businesses are investing in AI capabilities and preparing employees to use them. In EY India’s 2025 survey of 85 corporate treasury leaders, 82% reported that their organisations were planning or actively progressing toward AI adoption.
Where Is AI Already Being Used in Accounting Workflows?
AI is already being used across accounting workflows to automate repetitive tasks, identify discrepancies, and improve financial analysis. For Indian finance teams, its practical applications extend from everyday bookkeeping to compliance checks, cash flow forecasting, and audit preparation.
Invoice Processing and Data Entry
AI-powered tools extract supplier details, invoice numbers, amounts, and tax information from invoices. They can also suggest expense categories, identify potential duplicates, and route invoices for approval, reducing manual data entry.
Bank Reconciliation and Matching
AI matches bank transactions with general ledger entries using transaction amounts, dates, descriptions, and historical patterns. It flags unmatched transactions and potential discrepancies for accountants to investigate.
Expense Categorisation and Fraud Detection
AI analyses transaction patterns to suggest appropriate expense categories and identify unusual payments, duplicate claims, or unexpected spending. These alerts help finance teams investigate potential errors or fraud rather than relying solely on manual reviews.
Financial Forecasting and Cash Flow Prediction
AI analyses historical revenue, expenses, receivables, and payment patterns to support cash flow forecasts and budgeting. Finance teams can use these insights to anticipate cash shortages, evaluate different scenarios, and plan future spending.
GST and TDS Compliance Checks
AI can assist with invoice validation, GST data matching, TDS reconciliation, and identifying discrepancies in tax records. For example, it can help compare purchase records with GSTR-2B data, while accountants remain responsible for verifying eligibility, applicable tax rules, and filing accuracy.
Audit Support and Anomaly Detection
AI can review large transaction datasets, identify unusual journal entries, detect missing documentation, and flag inconsistencies. This kind of AI in auditing doesn’t replace the auditor’s judgement, but it narrows down which transactions are worth a closer look, helping auditors and finance teams focus their reviews while maintaining human oversight of audit conclusions.
What Are the Benefits of AI for Indian Finance Teams Specifically?
AI helps Indian finance teams reduce manual accounting work, improve accuracy, manage growing transaction volumes, and deliver faster financial insights. Its benefits are particularly relevant for businesses handling GST and TDS requirements, frequent digital transactions, and increasing reporting demands.
- Reduced Manual Work and Faster Processing:Automating repetitive activities such as invoice data extraction, transaction categorisation, and bank reconciliation. This allows finance teams to process larger transaction volumes without a proportional increase in manual effort.
- Improved Accuracy and Fewer Accounting Errors: AI identifies potential duplicate entries, mismatched transactions, and unusual amounts before they affect financial reports. Accountants can focus on reviewing flagged exceptions rather than checking every transaction manually.
- More Efficient GST and TDS Compliance: For GST and TDS compliance, AI can assist with invoice validation, reconciliations, tax calculations, and identifying discrepancies in tax records. This reduces the time spent preparing compliance data while keeping final verification with qualified professionals.
- Faster Month-End Closing: Automated transaction matching, reconciliations, and anomaly detection help finance teams identify outstanding issues earlier. This can reduce closing delays and improve the timeliness of financial reporting.
- Better Cash Flow Visibility: AI analyses historical transactions, payment patterns, and outstanding receivables to support cash flow forecasting. Finance teams can anticipate potential shortfalls and make more informed working capital decisions.
- Greater Focus on Strategic Financial Work: By reducing time spent on routine bookkeeping and data preparation, AI gives finance professionals more capacity for budgeting, profitability analysis, forecasting, and business advisory activities.
How to Implement AI in Your Accounting Workflow?
Implementing AI in accounting requires identifying suitable tasks, choosing tools that work with your existing systems, and maintaining appropriate human oversight. Indian finance teams can follow these five steps to introduce AI gradually while improving efficiency and maintaining financial accuracy.
Step 1: Identify Repetitive and Time-Consuming Accounting Tasks
Review your existing accounting processes to identify activities that involve significant manual effort. Invoice processing, transaction categorisation, bank reconciliation, expense verification, and routine financial reporting are potential starting points. Prioritise tasks with high transaction volumes, consistent procedures, and measurable opportunities for improvement.
Step 2: Evaluate Your Existing Accounting Systems and Data
Assess whether your current accounting software, ERP systems, and financial records can support AI integration. Check data accuracy, completeness, and consistency before introducing new tools. Identify integration requirements, access controls, and data security considerations, particularly when handling sensitive financial information.
Step 3: Select AI Tools That Fit Your Business Needs
Choose AI tools based on your accounting requirements, transaction volumes, and existing technology. For example, explore AI-enabled capabilities in accounting platforms such as Zoho Books, Tally, and NetSuite for invoice processing, reconciliations, and financial reporting. Evaluate integration capabilities, pricing, security features, audit trails, and support for Indian accounting workflows, including GST and TDS reconciliation. Prioritise solutions that address clearly defined problems rather than adopting AI features without a specific business purpose.
Step 4: Start with a Pilot and Establish Human Review
Begin with a limited pilot, such as AI-assisted invoice processing or bank reconciliation, before expanding to other accounting activities. Define approval procedures and assign accountants to review AI-generated entries, unusual transactions, and compliance-related outputs. Track errors and exceptions to identify where the workflow needs improvement.
Step 5: Train Your Finance Team and Measure Results
Provide practical training on using AI tools, interpreting their outputs, and identifying potential errors. Establish performance indicators such as processing time, reconciliation accuracy, exception rates, and hours saved. Compare results against your previous accounting processes and use employee feedback to refine workflows before scaling AI adoption.
How Can Finance Teams Measure the ROI of AI in Accounting?
Finance teams can measure the ROI of AI in accounting by comparing measurable improvements in efficiency, accuracy, and financial reporting against the total investment, including software subscriptions, system integration, employee training, maintenance, and ongoing human review. Indian businesses should establish performance benchmarks before implementation and track the following metrics to evaluate ROI:
- Time Saved on Manual Tasks: Compare the hours spent on invoice processing, bank reconciliation, data entry, and GST reconciliation before and after the implementation.
- Reduction in Processing Costs: Measure changes in the cost per invoice, transaction, or reconciliation, including savings from reduced manual effort and overtime.
- Improvement in Accounting Accuracy: Track duplicate entries, transaction mismatches, incorrect classifications, and the number of exceptions requiring manual correction.
- Faster Month-End Closing: Compare the number of days required to complete reconciliations, finalise accounts, and prepare financial reports before and after introducing AI.
- Compliance Efficiency: Measure the time spent preparing GST and TDS reconciliations, identifying discrepancies, and reviewing supporting documentation.
Streamline Your Finances with Expert AI in Accounting Services
AI in accounting helps Indian businesses reduce manual work, improve accuracy, and gain timely financial insights. From invoice processing and bank reconciliation to financial reporting and forecasting, combining AI with accounting expertise can improve efficiency while maintaining the human oversight needed for reliable financial decisions.
At Whiz Consulting, we combine accounting expertise with AI-enabled workflows to streamline routine tasks, maintain accurate financial records, and help your finance team focus on higher-value work. From automated bookkeeping and reconciliations to accounts payable, month-end closing, and financial reporting, we help reduce repetitive tasks, maintain accurate records, and give your internal finance team more time to focus on strategic business growth.

Get customized plan that supports your growth
Have questions in mind? Find answers here...
Yes. AI can assist Indian businesses with GST invoice validation, purchase register matching, GSTR-2B reconciliation, and identifying potential discrepancies. However, accountants should verify AI-generated results and ensure compliance with applicable GST requirements before filing returns.
Yes. ChatGPT can help accountants summarise financial reports, analyse trends, explain financial ratios, draft management reports, and support budgeting. However, its outputs must be verified, and businesses should avoid sharing confidential financial data without appropriate security safeguards.
Yes. Small businesses in India can use AI accounting software to automate invoice processing, expense categorisation, bank reconciliation, and financial reporting. The right solution depends on transaction volume, budget, existing software, and GST-related requirements.
The main risks include inaccurate outputs, data privacy concerns, cybersecurity threats, integration challenges, and excessive reliance on automated decisions. Businesses can reduce these risks through secure systems, regular accuracy checks, documented approval procedures, and human oversight.
AI is more likely to change accountants’ responsibilities than eliminate the profession. While it can automate repetitive bookkeeping and data processing, accountants remain essential for professional judgement, compliance reviews, complex financial decisions, and strategic advisory services.
Thousands of business owners trust Whiz to manage their account
Let us take care of your books and make this financial year a good one.